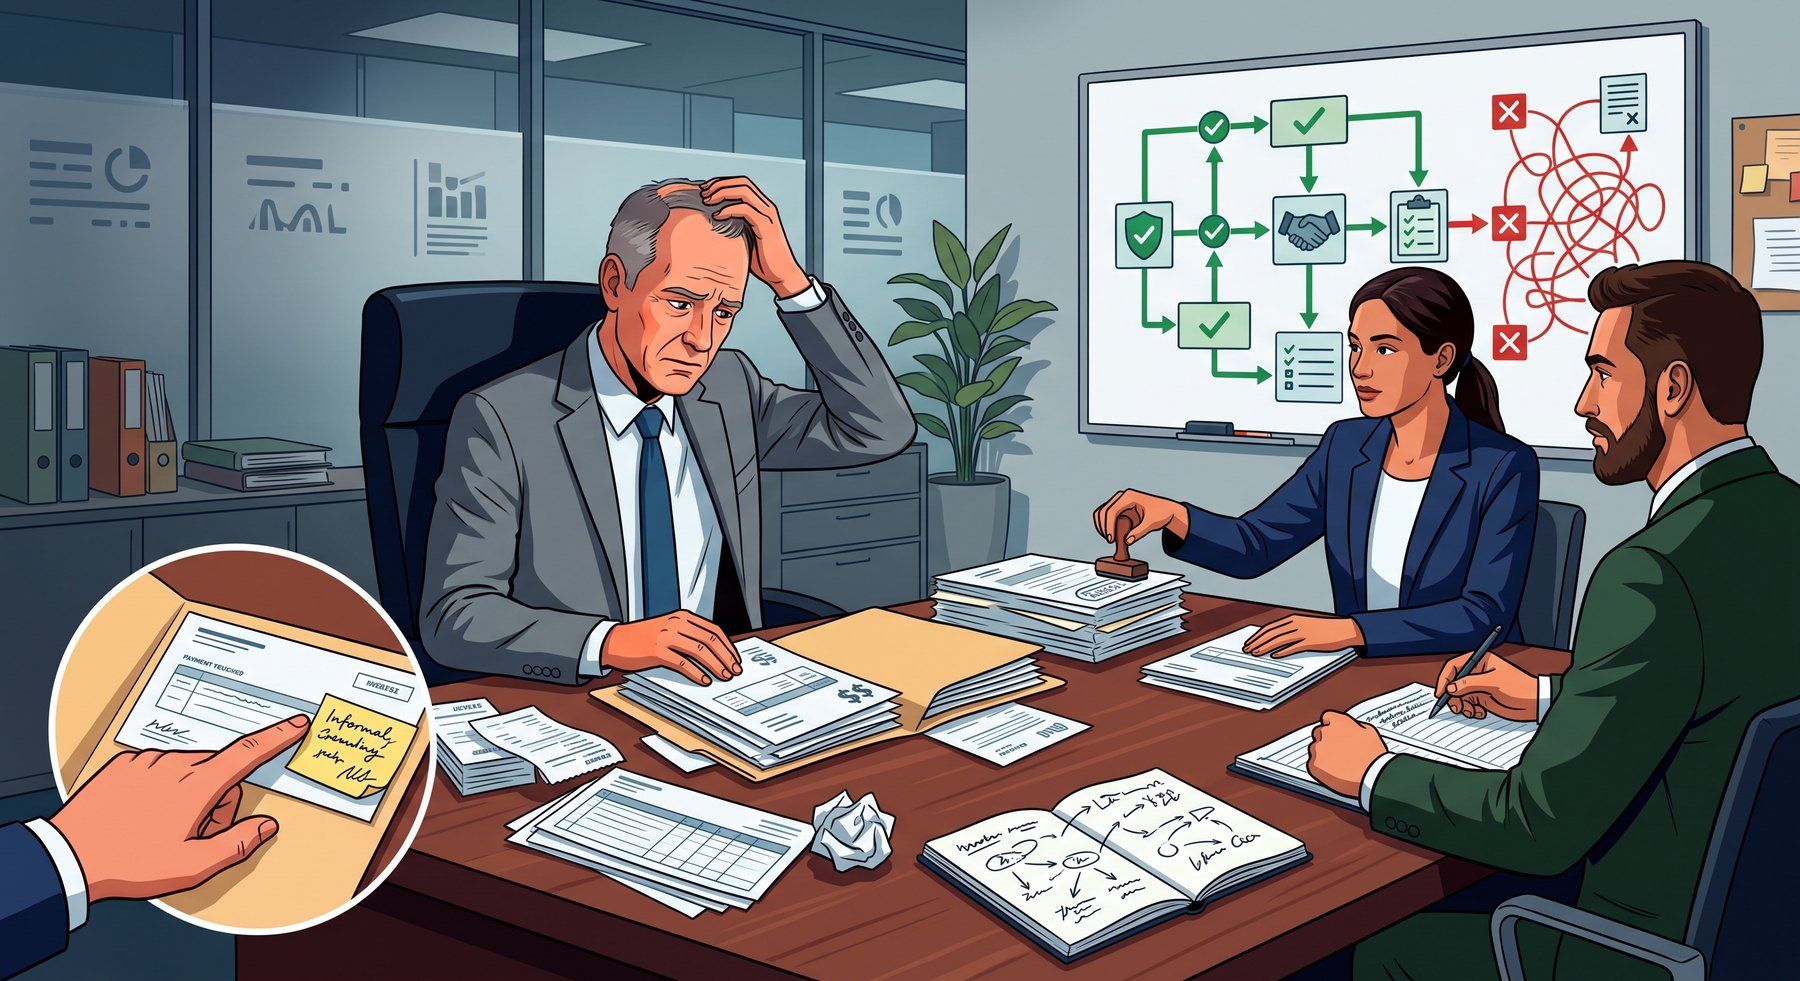
A Tangshan manufacturing manager is investigated for an alleged economic offense after payments to suppliers and an affiliate are questioned. The company historically relied on informal approvals, and the manager received personal payments from one supplier that he describes as repayment of an old private loan. If the supporting bank transfer and messages predate the supplier relationship, they can corroborate part of the explanation; if the documents appear only after investigation, the defense needs to address that weakness rather than treating the label “loan” as sufficient. The key is to separate company custom, actual decision authority, personal benefit and later compliance remediation.
Informal management has to be described precisely before it can explain a questioned transaction. Informal management has to be described precisely before it can explain a questioned transaction. Historic approval practice, actual authority and deviations from it need evidence. Informality matters only insofar as it explains authority or purpose; it cannot make a personal payment legitimate by itself. The most useful supporting records here are supplier contracts, bank transfers and conflict disclosures. [1][2]
The specific problem
The Legal Rule
A Tangshan manufacturing manager is investigated for an alleged economic offense after payments to suppliers and an affiliate are questioned.
The Business Impact
Obtain counsel early, preserve transaction and communications records, and coordinate any explanation given to investigators. The first procedural decisions can affect detention, access to evidence and the theory of the case. Apply that to the facts of When a Tangshan Manager Faces an Economic-Crime Investigation: Authority, Personal Benefit, Company Practice and Compliance Remediation.
Informal management should be documented rather than romanticized
The defense should therefore separate legitimate supplier arrangements, genuine private transactions and unexplained transfers. Compliance findings can identify a control failure while the criminal case still needs proof of the manager’s own conduct and state of mind. If money is returned, the legal purpose and amount should be documented rather than allowed to blur the merits theory. Forward-looking compliance measures belong in a separate remediation record so they do not rewrite the historical transaction. Applied to “Informal management should be documented rather than romanticized,” that produces a section-specific recommendation rather than a reusable evidence checklist. For informal management should be documented rather than romanticized, the company’s historic process should be compared with the questioned transaction so departures from ordinary practice are visible rather than assumed.
Personal benefit is a separate factual question
Informal management has to be described precisely before it can explain a questioned transaction. Informal management has to be described precisely before it can explain a questioned transaction. Supplier payments, loan documents and timing should be traced independently from company transactions. The questioned management practice should be described in operational terms: who proposed, approved, paid and benefited. The most useful supporting records here are accounting entries, loan records and procurement approvals. [1][2]
Compliance findings can identify control failures while the criminal case still requires proof of the manager’s own intent and benefit. Compliance findings can identify a control failure while the criminal case still needs proof of the manager’s own conduct and state of mind. If money is returned, the legal purpose and amount should be documented rather than allowed to blur the merits theory. The section should end by classifying the transaction as explained, disputed or unsupported and by stating what that classification changes in the case. Applied to “Personal benefit is a separate factual question,” that produces a section-specific recommendation rather than a reusable evidence checklist. For personal benefit is a separate factual question, the company’s historic process should be compared with the questioned transaction so departures from ordinary practice are visible rather than assumed.
Related-party transactions need proof of real goods or services
A manager’s title says little unless the payment, supplier and approval process are mapped around it. A manager’s title says little unless the payment, supplier and approval process are mapped around it. Contracts, pricing, delivery and business purpose should be tested. The questioned management practice should be described in operational terms: who proposed, approved, paid and benefited. The most useful supporting records here are conflict disclosures, procurement approvals and bank transfers. [1][3]
Historic practice can provide context, but it cannot turn a prohibited personal benefit into ordinary business. Supplier substance, private-loan evidence and committee decision-making should therefore be documented independently. If money is returned, the legal purpose and amount should be documented rather than allowed to blur the merits theory. Forward-looking compliance measures belong in a separate remediation record so they do not rewrite the historical transaction. Applied to “Related-party transactions need proof of real goods or services,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should separate related-party transactions need proof of real goods or services from legitimate supplier or private transactions and identify the remaining unexplained amount.
Job title should be separated from actual decision power
A manager’s title says little unless the payment, supplier and approval process are mapped around it. The relevant issue is how this company actually made the decision under review. Who selected suppliers, negotiated price, approved contract and released payment may differ. Informality matters only insofar as it explains authority or purpose; it cannot make a personal payment legitimate by itself. The most useful supporting records here are committee minutes, supplier contracts and bank transfers. [1][3]
Historic practice can provide context, but it cannot turn a prohibited personal benefit into ordinary business. Compliance findings can identify a control failure while the criminal case still needs proof of the manager’s own conduct and state of mind. Remediation belongs in a forward-looking file; the historical defense belongs in the transaction record. Forward-looking compliance measures belong in a separate remediation record so they do not rewrite the historical transaction. Applied to “Job title should be separated from actual decision power,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should separate job title should be separated from actual decision power from legitimate supplier or private transactions and identify the remaining unexplained amount.
Internal compliance findings are not the same as criminal findings
The relevant issue is how this company actually made the decision under review. A manager’s title says little unless the payment, supplier and approval process are mapped around it. Policy breaches can be relevant without satisfying the offense. The questioned management practice should be described in operational terms: who proposed, approved, paid and benefited. The most useful supporting records here are conflict disclosures, accounting entries and bank transfers. [1][2]
Compliance findings can identify control failures while the criminal case still requires proof of the manager’s own intent and benefit. Supplier substance, private-loan evidence and committee decision-making should therefore be documented independently. If money is returned, the legal purpose and amount should be documented rather than allowed to blur the merits theory. Forward-looking compliance measures belong in a separate remediation record so they do not rewrite the historical transaction. Applied to “Internal compliance findings are not the same as criminal findings,” that produces a section-specific recommendation rather than a reusable evidence checklist. For internal compliance findings are not the same as criminal findings, the company’s historic process should be compared with the questioned transaction so departures from ordinary practice are visible rather than assumed.
Accounting and bank records should be synchronized
A manager’s title says little unless the payment, supplier and approval process are mapped around it. Informal management has to be described precisely before it can explain a questioned transaction. Ledger treatment, invoice, approval and cash movement should tell one coherent story. The questioned management practice should be described in operational terms: who proposed, approved, paid and benefited. The most useful supporting records here are committee minutes, bank transfers and loan records. [2][4]
The defense should therefore separate legitimate supplier arrangements, genuine private transactions and unexplained transfers. Supplier substance, private-loan evidence and committee decision-making should therefore be documented independently. The strongest position explains company practice without asking the court to treat informality as immunity. The section should end by classifying the transaction as explained, disputed or unsupported and by stating what that classification changes in the case. Applied to “Accounting and bank records should be synchronized,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should separate accounting and bank records should be synchronized from legitimate supplier or private transactions and identify the remaining unexplained amount.
Other managers’ roles may narrow personal attribution
A manager’s title says little unless the payment, supplier and approval process are mapped around it. A manager’s title says little unless the payment, supplier and approval process are mapped around it. Committee approvals and shared responsibility should be mapped without diffusing genuine individual conduct. The questioned management practice should be described in operational terms: who proposed, approved, paid and benefited. The most useful supporting records here are loan records, procurement approvals and conflict disclosures. [1][3]
The defense should therefore separate legitimate supplier arrangements, genuine private transactions and unexplained transfers. Compliance findings can identify a control failure while the criminal case still needs proof of the manager’s own conduct and state of mind. Remediation belongs in a forward-looking file; the historical defense belongs in the transaction record. The section should end by classifying the transaction as explained, disputed or unsupported and by stating what that classification changes in the case. Applied to “Other managers’ roles may narrow personal attribution,” that produces a section-specific recommendation rather than a reusable evidence checklist. For other managers’ roles may narrow personal attribution, the company’s historic process should be compared with the questioned transaction so departures from ordinary practice are visible rather than assumed.
Compliance remediation can proceed without conceding criminal intent
Informal management has to be described precisely before it can explain a questioned transaction. The relevant issue is how this company actually made the decision under review. New controls, repayment and supplier review address future risk. Informality matters only insofar as it explains authority or purpose; it cannot make a personal payment legitimate by itself. The most useful supporting records here are bank transfers, loan records and accounting entries. [1][2]
Historic practice can provide context, but it cannot turn a prohibited personal benefit into ordinary business. Compliance findings can identify a control failure while the criminal case still needs proof of the manager’s own conduct and state of mind. The strongest position explains company practice without asking the court to treat informality as immunity. The section should end by classifying the transaction as explained, disputed or unsupported and by stating what that classification changes in the case. Applied to “Compliance remediation can proceed without conceding criminal intent,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should separate compliance remediation can proceed without conceding criminal intent from legitimate supplier or private transactions and identify the remaining unexplained amount.
Restitution or return of funds needs a documented legal purpose
The relevant issue is how this company actually made the decision under review. The relevant issue is how this company actually made the decision under review. Payment should not silently accept an inflated criminal amount. The questioned management practice should be described in operational terms: who proposed, approved, paid and benefited. The most useful supporting records here are accounting entries, bank transfers and loan records. [1][2]
The defense should therefore separate legitimate supplier arrangements, genuine private transactions and unexplained transfers. Supplier substance, private-loan evidence and committee decision-making should therefore be documented independently. If money is returned, the legal purpose and amount should be documented rather than allowed to blur the merits theory. The section should end by classifying the transaction as explained, disputed or unsupported and by stating what that classification changes in the case. Applied to “Restitution or return of funds needs a documented legal purpose,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should separate restitution or return of funds needs a documented legal purpose from legitimate supplier or private transactions and identify the remaining unexplained amount.
Compliance remediation should have its own chronology and evidentiary purpose
Once a company discovers a procurement or conflict-of-interest problem, management may need to tighten controls immediately. New supplier checks, dual approval, conflict declarations and repayment procedures can reduce continuing risk. Those steps should be recorded from the date they are adopted and linked to the problem they are intended to correct. They are evidence of the company’s response, not a substitute for proving what a particular manager did earlier. [1][3]
The individual defense should therefore keep two files conceptually separate. The historical file contains the questioned transfers, procurement decisions, authority records and evidence of any personal benefit. The remediation file shows what the company changed after the issue surfaced. Combining them can create confusion: a later rule requiring two signatures does not prove that a one-signature process was criminal before the rule existed, and a repayment does not answer whether the original transfer had a legitimate basis.
This distinction is also important to plea or mitigation decisions. A manager may support remediation and return disputed funds while continuing to contest the prosecution’s characterization of intent or amount. If the case later moves toward confession and punishment, the admitted facts should be stated precisely. Compliance improvement is valuable, but it should not pressure the client into accepting a broader historical narrative than the source evidence supports. If the company disciplines another employee for the same transaction, that action should be recorded separately from the evidence used to attribute criminal responsibility to the manager.
A private-loan explanation should be proved independently of the supplier relationship
When a manager receives money from a supplier and describes it as repayment of an old personal loan, the defense should treat the loan as a separate transaction requiring its own proof. Bank records showing the original advance, messages predating the supplier relationship, repayment discussions and consistent amounts can corroborate the explanation. The existence of a genuine loan for part of the money does not explain additional transfers automatically, and the defense should not allow one supported transaction to become a blanket account of every payment. [1][2]
The supplier relationship should then be analyzed on its own. Did the manager influence selection, pricing or payment? Was the supplier already doing business with the company before the personal relationship? Did the manager disclose the relationship or participate in decisions despite a conflict? These facts bear on the prosecution’s inference about benefit and intent. Committee approval can be relevant, but it does not erase personal conduct if the manager manipulated the information provided to the committee.
This separation strengthens credibility. The defense can concede that an unexplained balance requires further analysis while demonstrating that the prosecution’s gross personal-payment figure overstates the amount actually in issue. If repayment or restitution later occurs, the schedule should identify which amount corresponds to the private loan, which relates to the company and which remains disputed. That keeps mitigation from obscuring the merits.
Where the company later terminates or disciplines another participant, that employment decision should be kept separate from the manager’s criminal file. Internal discipline may use a lower factual threshold or address policy breaches rather than the charged offense. The defense should use the underlying records, not the disciplinary label, when comparing the roles of multiple managers.
Case study: applying the framework
Assume the manager helped select a supplier, sat on a three-person approval committee and received RMB 240,000 from the supplier’s owner over two years. He produces evidence of a RMB 150,000 private loan predating the business relationship; the remaining payments have no clear written explanation.
The claimed private loan should be tested from its beginning rather than from the manager’s explanation after investigation. Bank records, messages and any earlier repayment schedule could corroborate RMB 150,000 of the transfers, while the unexplained balance would remain a separate issue. The approval committee also matters: if supplier price and contract terms required three votes, the prosecution should identify what the manager controlled beyond one vote. At the same time, informal company practice cannot excuse a hidden personal benefit. Remediation can tighten procurement controls and recover funds, but the personal defense still depends on whether the historical evidence proves corrupt purpose, unauthorized use or another charged economic offense.
If the RMB 150,000 loan is corroborated, the remaining RMB 90,000 should still be analyzed on its own facts. The defense should not use a genuine loan to explain unrelated transfers. The committee process should likewise be reconstructed from meeting records and payment controls to identify what the manager actually decided. Any company remediation—new supplier due diligence, conflict declarations or dual approvals—would be documented as a forward-looking control change rather than a substitute for the historical criminal analysis. The company would retain the remediation records separately so later compliance improvements are not confused with the historical defense evidence. If the manager repays the unexplained balance while maintaining that no criminal benefit was intended, the defense should document the payment as remediation without describing it as an admission. The prosecution and court can then consider the repayment for harm and mitigation while the original purpose of the transfer remains a separate merits issue. The manager’s repayment schedule should also identify whether money was returned to the supplier, the company or another person, because the recipient can matter to both commercial explanation and mitigation. Where the supplier relationship continues after remediation, the company should document who now approves pricing and payments so later transactions are not confused with the historical period under investigation.
Conclusion
Managerial informality can explain how a company operated, but it cannot replace the criminal-law analysis. Supplier substance, authority, personal benefit and committee decision-making should be reconstructed transaction by transaction. Compliance remediation is useful for future risk and may matter to mitigation, yet it should remain separate from the historical merits record. The strongest defense explains genuine business practice while confronting unexplained personal payments or other adverse facts directly.
Legal and regulatory sources
[1] Criminal Law of the People’s Republic of China — [official source](https://gongbao.court.gov.cn/Details/96fea4e0b9e00def2295a1e598666f.html) [2] Criminal Procedure Law of the People’s Republic of China — [official source](https://gongbao.court.gov.cn/Details/f0b554c8af1a1ed9dbaa58bb9e62c3.html) [3] Company Law of the People’s Republic of China (2023 revision) — [official source](https://www.npc.gov.cn/npc/c2/c30834/202312/t20231229_433999.html) [4] SPC/SPP/MPS Provisions on Electronic Data in Criminal Cases — [official source](https://www.court.gov.cn/fabu/xiangqing/26431.html) [5] 2026 Five-Authority Guidance on Leniency for Confession and Acceptance of Punishment — [official source](https://www.court.gov.cn/zixun/xiangqing/506411.html)
General legal information only; not legal advice for a specific matter.
Discussion
Share experience or questions about this topic. This is a public discussion — not legal advice. Do not post confidential case details.
Have a question after reading? Leave it here, or Ask a Lawyer for a free initial intake.
Comments are moderated. China Legal Portal is a directory and information resource; no attorney–client relationship is formed by posting here.