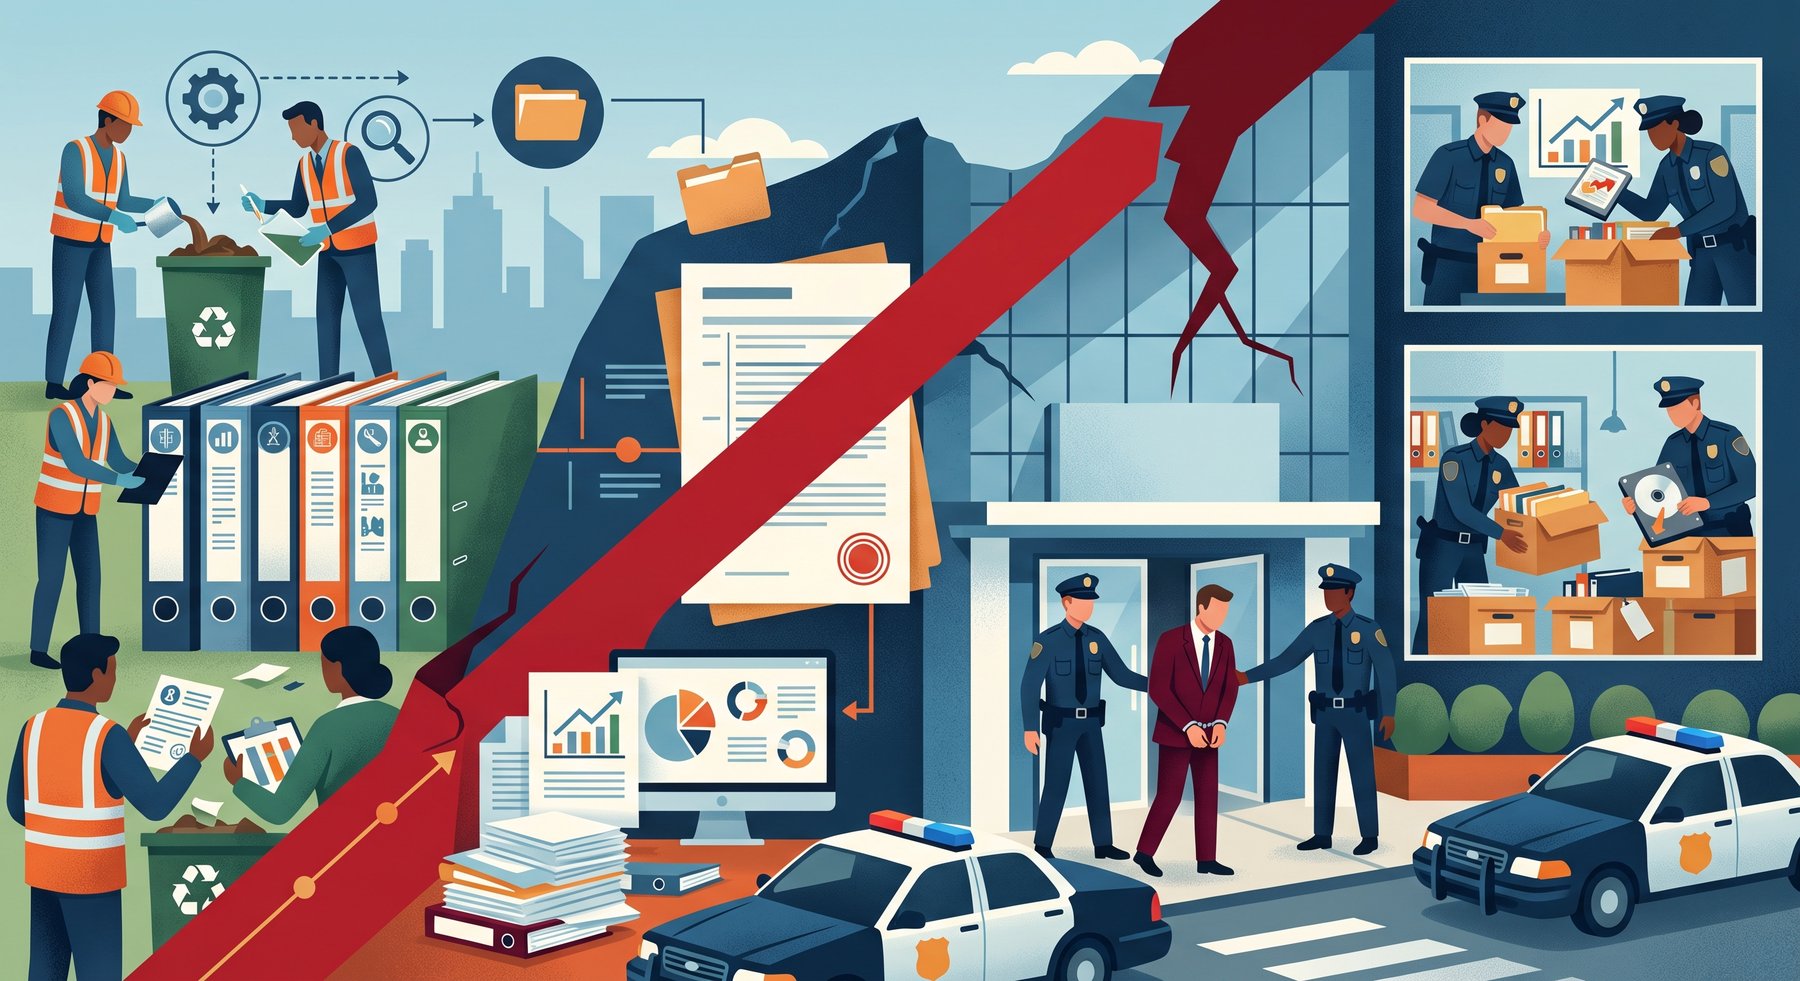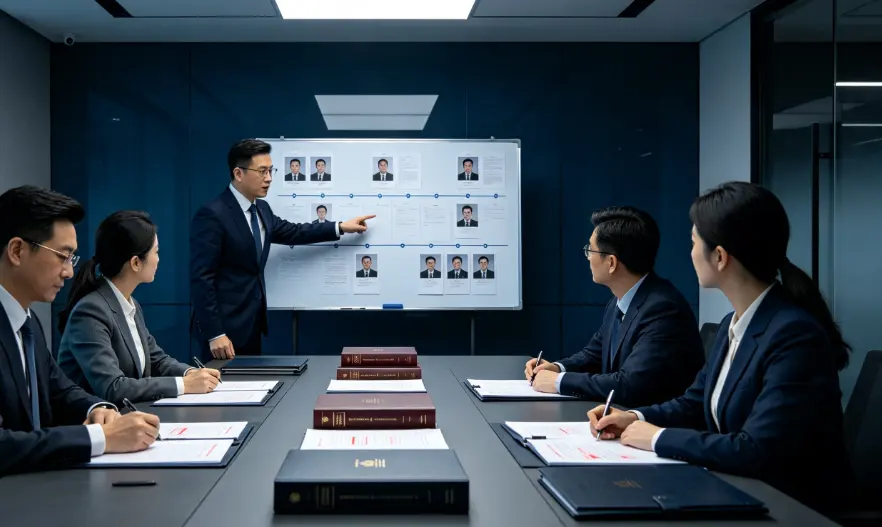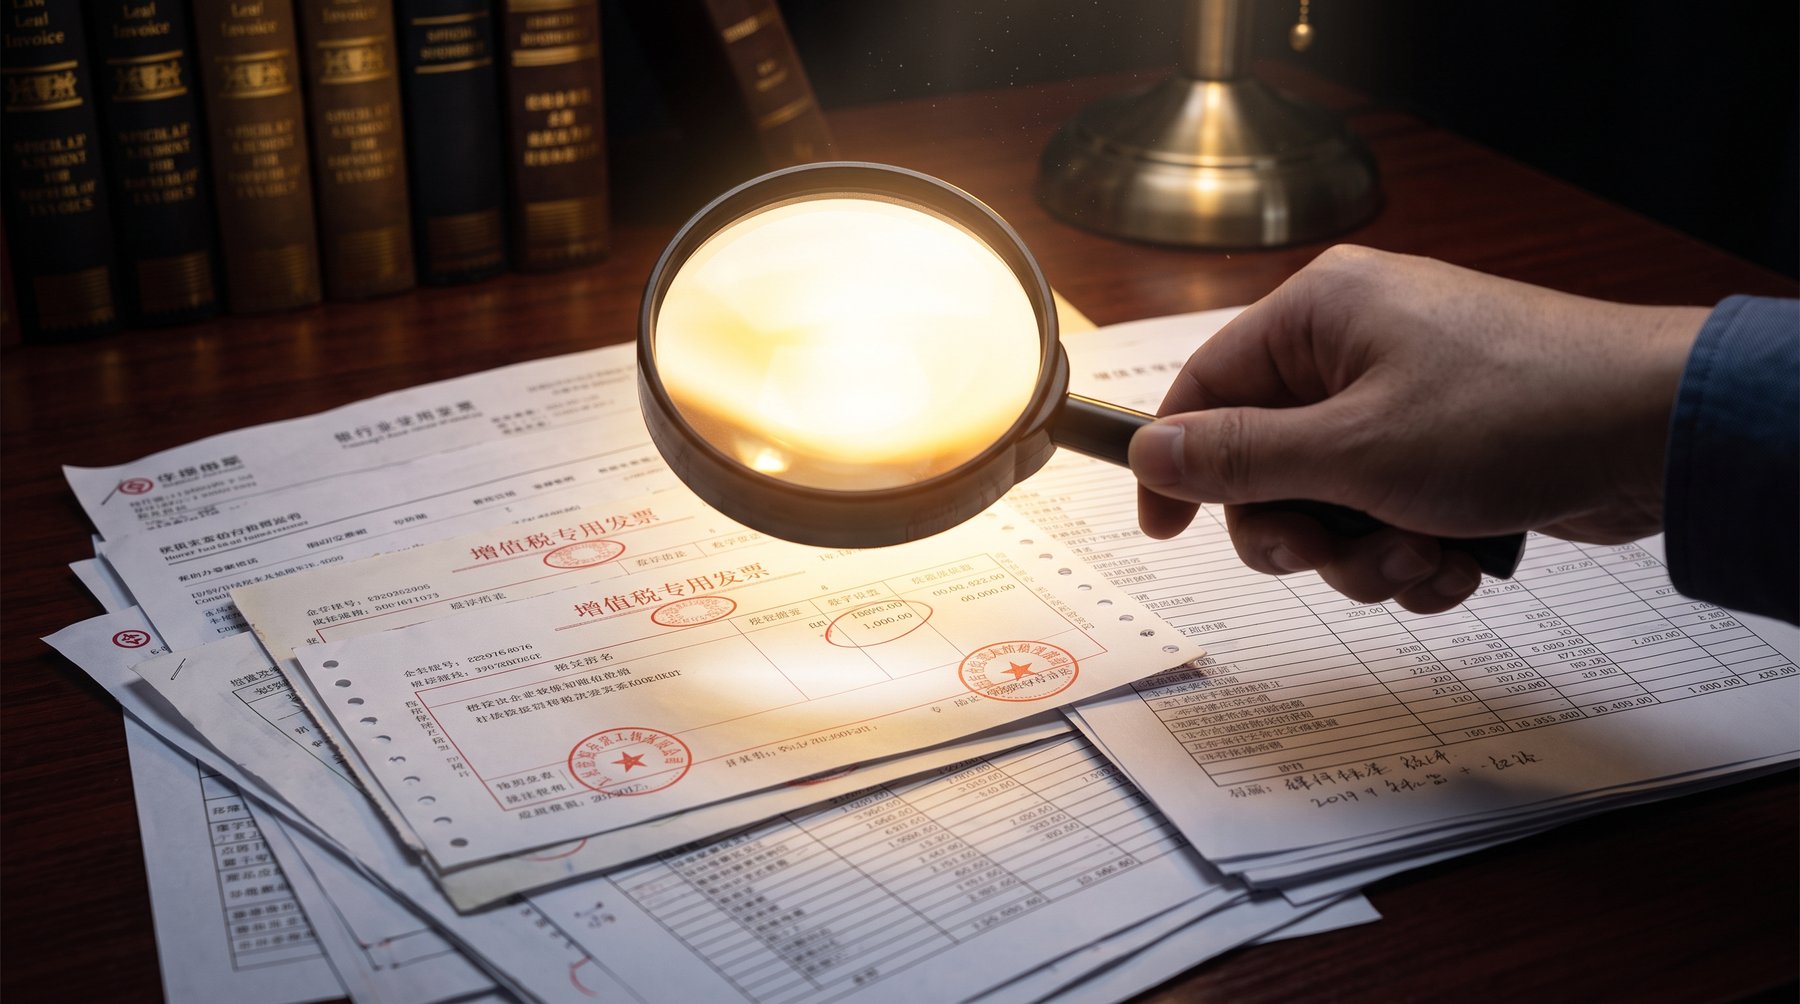
A Nanjing trading company receives a tax inquiry concerning special VAT invoices issued by several suppliers. Management initially sees a routine tax audit, but questions about circular fund flows and nonexistent deliveries suggest possible criminal exposure. The first task is not to argue legal conclusions. It is to preserve the transaction record and reconstruct whether each challenged invoice corresponds to genuine goods or services, real payment and actual commercial purpose.
China's VAT Law took effect on January 1, 2026 and provides the current statutory VAT framework. Tax administration and criminal enforcement remain distinct but can intersect where authorities suspect false invoicing or fraudulent tax treatment. The Criminal Law contains offenses relevant to false issuance of special VAT invoices and fraudulent export tax rebate conduct, while the Criminal Procedure Law governs criminal investigative procedure.
The specific issue
The Legal Rule
A Nanjing trading company receives a tax inquiry concerning special VAT invoices issued by several suppliers.
The Business Impact
Obtain counsel early, preserve transaction and communications records, and coordinate any explanation given to investigators. The first procedural decisions can affect detention, access to evidence and the theory of the case. Apply that to the facts of The First 72 Hours of a Suspected False Special VAT Invoice Investigation: Reconstructing Transaction Substance Before Tax Risk Becomes Criminal Risk.
1. Treat the inquiry as potentially both tax-administrative and criminal-risk work
Treat the first inquiry as potentially both a tax-administrative matter and a criminal-risk event. Parallel tracks require coordinated counsel, evidence control and messaging. Assuming “it is only a tax reconciliation” is how companies create inconsistent statements that later appear intentional.
2. Preserve contracts, invoices, accounting, logistics, bank flow and communications immediately
Immediately preserve contracts, invoices, accounting vouchers, logistics records, inventory ledgers, bank flows and relevant communications under a hold notice. Do not wait for a formal list. Early deletion or “cleanup” of chats is often worse than the underlying invoice defect.
3. Build a transaction-by-transaction matrix instead of defending by supplier name only
Build a transaction-by-transaction matrix for challenged invoices: parties, goods or services, quantities, amounts, warehouses, transport, acceptance and payment. Defending only at the supplier-name level hides which deals are real, weak or fabricated.
4. Prove what goods or services actually moved and why the transaction existed
Prove what moved commercially and why the deal existed: purchase need, production use, resale and counterparty capability. Invoice stationery without commercial purpose is the core narrative in false special VAT invoice cases.
5. Compare invoice descriptions with logistics, inventory and acceptance evidence
Compare invoice item descriptions with logistics documents, warehouse in/out records and acceptance evidence. Mismatches between what was billed and what can be shown to have moved are priority reconstruction targets in the first seventy-two hours.
6. Trace funds for circular transfers, cash returns and unrelated recipients
Trace funds for circular transfers, rapid cash returns and payments to unrelated recipients. Fund flows that do not match the trade path are often the fact pattern that shifts a matter from documentation weakness toward suspected fraud.
7. Interview process custodians before suspected individuals where appropriate
Interview process custodians—warehouse, logistics, accounting clerks—before confrontational interviews of suspected decision-makers, where appropriate. Custodians often establish how paperwork actually worked; early coaching of managers contaminates that baseline.
8. Prevent managers from coaching witnesses or rewriting transaction histories
Prohibit managers from coaching witnesses, rewriting vendor stories or creating backdated contracts. New paperwork invented after notice is usually identifiable and damages credibility for the genuine transactions the company needs to save.
9. Separate tax error, documentation weakness and suspected intentional fraud
Separate tax error, weak documentation and suspected intentional false invoicing in the internal analysis. Not every irregular invoice is criminal, but treating a potentially serious pattern as a routine amendment problem can under-prepare the company for investigative measures.
10. Review supplier onboarding and beneficial ownership
Review supplier onboarding files and beneficial ownership. Shell vendors with shared addresses, newly formed entities and overlapping controllers frequently appear in false-invoice networks. Onboarding gaps also show whether controls failed once or systematically.
11. Update invoicing controls to reflect the 2026 VAT Law framework
Update invoicing and input-credit controls against the VAT Law framework effective 2026 rather than relying only on legacy administrative habits. Process fixes should begin during the crisis response so the company is not only reconstructing the past.
12. Where export rebates are involved, reconcile customs, logistics and rebate records
Where export rebates are implicated, reconcile customs declarations, logistics, forex receipts and rebate filings with the invoice chain. Export-linked false invoicing theories often turn on inconsistencies across those datasets.
13. Assess voluntary correction or disclosure only after facts are understood
Assess voluntary correction or disclosure only after the factual matrix is understood. Premature admissions without transaction-level analysis can mis-label legitimate deals; delayed action after clear fraud indicators can worsen exposure. Timing is a counsel judgment, not a reflex.
14. Create a single company contact protocol for tax and police inquiries
Create a single contact protocol for tax authorities and public-security inquiries: named spokespersons, document logs and no informal employee interviews without coordination. Mixed messages from multiple managers are a recurring early failure.
15. Prepare for document collection or compulsory investigative measures
Prepare for document collection or compulsory measures by organizing source files, access credentials and privilege protocols. Panic searching after officers arrive produces gaps; a prepared collection map reduces error and demonstrates cooperation discipline.
16. Use a hypothetical trading company with three suspect suppliers and circular funds
In a typical trading-company pattern with several suspect suppliers and circular funds, force the team to classify each supplier’s invoices into supported, unsupported and mixed within seventy-two hours. That triage drives preservation, interview order and board reporting.
17. Report factual scenarios to the board without premature criminal labels
Report to the board in factual scenarios and exposure ranges without premature criminal labels. Directors need to authorize budget, hold notices and external counsel; they do not need speculative conclusions that later conflict with the evidence.
18. Suspend high-risk counterparties and strengthen three-way matching
Suspend high-risk counterparties and impose three-way matching among purchase order, receipt and invoice before further payments. Continuing to trade with suspect vendors during the inquiry compounds exposure and weakens the remediation narrative.
19. Conduct a historical lookback to quantify repeated exposure
Run a historical lookback across periods and entities to quantify how often the pattern repeats. A single-supplier incident and a multi-year network imply different reserves, disclosure and defense strategies.
20. Do not finish the first 72 hours until every challenged invoice is linked to a real transaction evidence file
Do not close the first seventy-two hours until every challenged invoice in the initial set is linked to a real-transaction hypothesis, an unsupported-fraud hypothesis or a documented information gap with an owner. Unclassified invoices are unfinished work.
Worked scenario: three suppliers, real invoices and uncertain underlying trade
Assume a Nanjing trading company is questioned about special VAT invoices issued by three suppliers. The invoices were booked and paid. However, warehouse records are incomplete, several delivery notes are missing, and part of the funds appears to have returned through accounts linked to intermediaries. One supplier has recently been investigated by authorities. Management wants to explain that “all invoices were approved by finance.”
That answer is inadequate because invoice approval does not prove transaction substance. The company should build a separate file for each challenged invoice or transaction batch. It should identify the purchase contract, commercial purpose, goods or services, delivery location, receiving personnel, inventory movement, onward sale, payment and any later fund transfer. Where evidence is missing, the file should say so rather than invent a narrative.
Bank-flow analysis is critical. A payment that returns to the company, an employee or an unrelated account shortly after invoicing requires explanation. It may have a legitimate reason, but counsel should verify the documentary basis before anyone gives a statement. Logistics and warehouse data should be reconciled with invoice descriptions and accounting entries.
Employee interviews should be sequenced. Procurement and warehouse personnel can first explain ordinary business processes. Finance can explain invoice review and payment. Only after the transaction map is understood should the team interview people suspected of arranging unusual flows. Interview notes should distinguish what the person directly observed from assumptions based on routine practice.
The legal team should keep tax and criminal analysis separate until the facts are reconstructed. A tax adjustment, unsupported deduction and alleged intentional false invoicing are not the same legal problem. The 2026 VAT Law should guide current compliance, while any potential criminal exposure must be assessed under the Criminal Law and criminal procedure.
During the first 72 hours, the goal is therefore control of evidence and communications. The company should preserve systems, designate one external-contact channel, suspend high-risk counterparties if appropriate and brief the board using factual scenarios rather than premature conclusions about guilt.
Action checklist before implementation
- Confirm who has authority to speak for the company and to approve holds or suspensions.
- Assemble the core evidence set: invoice list, contracts, logistics, inventory, bank flows, communications and supplier onboarding files.
- Identify the transactions most likely to be characterized as lacking commercial substance and verify them first.
- Quantify exposure ranges without premature criminal labels.
- List custodians who must be interviewed and systems that must be imaged.
- Define the fallback if compulsory measures begin before reconstruction is finished.
- Reconcile tax, customs and accounting datasets where export rebates are involved.
- Assign owners for the transaction matrix and contact protocol.
- Ensure no manager coaches witnesses or creates backdated papers.
- Retain the seventy-two-hour file linking each challenged invoice to a hypothesis.
Quality-control questions
Before the matter is closed, an independent reviewer should be able to reconstruct the transaction matrix, preservation steps and board reporting for the first seventy-two hours. The reviewer should explain why the team avoided allowing employees to give inconsistent explanations before the evidence baseline was fixed. If that explanation depends on recollection rather than the file, the work is not complete.
Decision tree during the first 72 hours
The first question is whether the company understands which invoices and periods are actually under review. Counsel should obtain the inquiry materials, identify the relevant suppliers and freeze records before employees start reconstructing documents. A broad instruction to “find everything about VAT” can overwhelm the response and contaminate the chronology.
The second step is to classify the factual weakness. Some invoices may correspond to real purchases but have documentation gaps. Others may show payment without delivery. Still others may involve circular funds or parties with no apparent capacity to supply the goods. These categories should not be defended with one explanation.
The third step is to control communications. One designated legal or management contact should coordinate with tax authorities and, if involved, police. Employees should be instructed to preserve records and answer truthfully but not to speculate or align stories. Interviews should be conducted in a sequence that first explains normal business processes and then tests anomalies.
Only after the transaction map is built should counsel assess whether the matter is a tax adjustment, administrative violation or potential criminal issue. Premature legal labels can distort interviews and board reporting.
Transaction-substance evidence file
For each challenged invoice, the file should identify the contract, purchase order, invoice, payment, goods or services, delivery record, warehouse entry, acceptance, onward sale and responsible employees. Where a link is missing, the team should identify what alternative evidence exists, such as customer delivery, third-party logistics or inventory movement.
Bank analysis should extend beyond the first payment. Investigators should look for rapid return of funds, transfers to employees or intermediaries, cash withdrawals and patterns across suppliers. Legitimate commercial explanations should be documented with source evidence.
Supplier due diligence should review ownership, business scope, staff, premises, historical transactions and relationship with employees. A new supplier that suddenly generates large VAT invoices without operational capacity deserves deeper review.
Board reporting should be factual and scenario-based. It should quantify the amount under review, explain the evidence strength by supplier, identify whether authorities have escalated the matter and state immediate controls such as suspending purchases or tightening three-way matching. Management needs an accurate risk picture, not an unsupported conclusion that the company is either safe or criminally exposed.
Internal controls to implement while the investigation is still open
The company should immediately tighten supplier onboarding for the affected business line. New suppliers should be checked for business scope, operating capacity, beneficial ownership, bank-account consistency and relationship to employees. High-value suppliers should not be activated solely on the recommendation of one commercial employee.
Three-way matching should be strengthened so that invoice approval is connected to purchase order and receiving evidence. Where the business model does not generate conventional warehouse records, the company should identify equivalent proof such as service acceptance, third-party logistics or customer delivery.
Finance should also monitor unusual payment patterns. Payments to accounts different from the contracted supplier, rapid refund flows, cash withdrawals and repeated round-number transfers should trigger escalation. The objective is not to treat every anomaly as fraud but to require documented explanation before the transaction is closed.
The board or audit committee should receive updates that distinguish confirmed facts, open questions and remedial steps. This preserves governance discipline while avoiding premature conclusions. If authorities later ask what the company did after discovering the issue, contemporaneous remediation records can show that management treated the risk seriously.
First-day communications protocol
Employees should receive a narrowly drafted preservation notice and a clear instruction that all external inquiries are routed through the designated response team. The company should not circulate speculation about criminal liability internally. Management should instead state which transactions are under review, which records must be preserved and who is authorized to communicate with authorities. This reduces inconsistent statements while keeping the investigation fact-based.
Conclusion
This issue should be managed as a specific legal-control problem. The legal framework must be applied to verified facts and converted into an executable sequence. The central lesson from this scenario is to avoid allowing employees to give inconsistent explanations before the company has reconstructed the real transaction flow and preserved source records. A strong file shows the legal rule, the commercial decision, the supporting evidence and the fallback if the preferred route fails.
Legal and regulatory sources
[1] VAT Law of the PRC, effective January 1, 2026: https://www.npc.gov.cn/npc/c2/c30834/202412/t20241225_442883.html [2] Criminal Law of the PRC — official NPC legal database: https://flk.npc.gov.cn/ [3] Criminal Procedure Law of the PRC — official NPC legal database: https://flk.npc.gov.cn/
This article is general legal information and is not legal advice for a specific matter.
Discussion
Share experience or questions about this topic. This is a public discussion — not legal advice. Do not post confidential case details.
Have a question after reading? Leave it here, or Ask a Lawyer for a free initial intake.
Comments are moderated. China Legal Portal is a directory and information resource; no attorney–client relationship is formed by posting here.