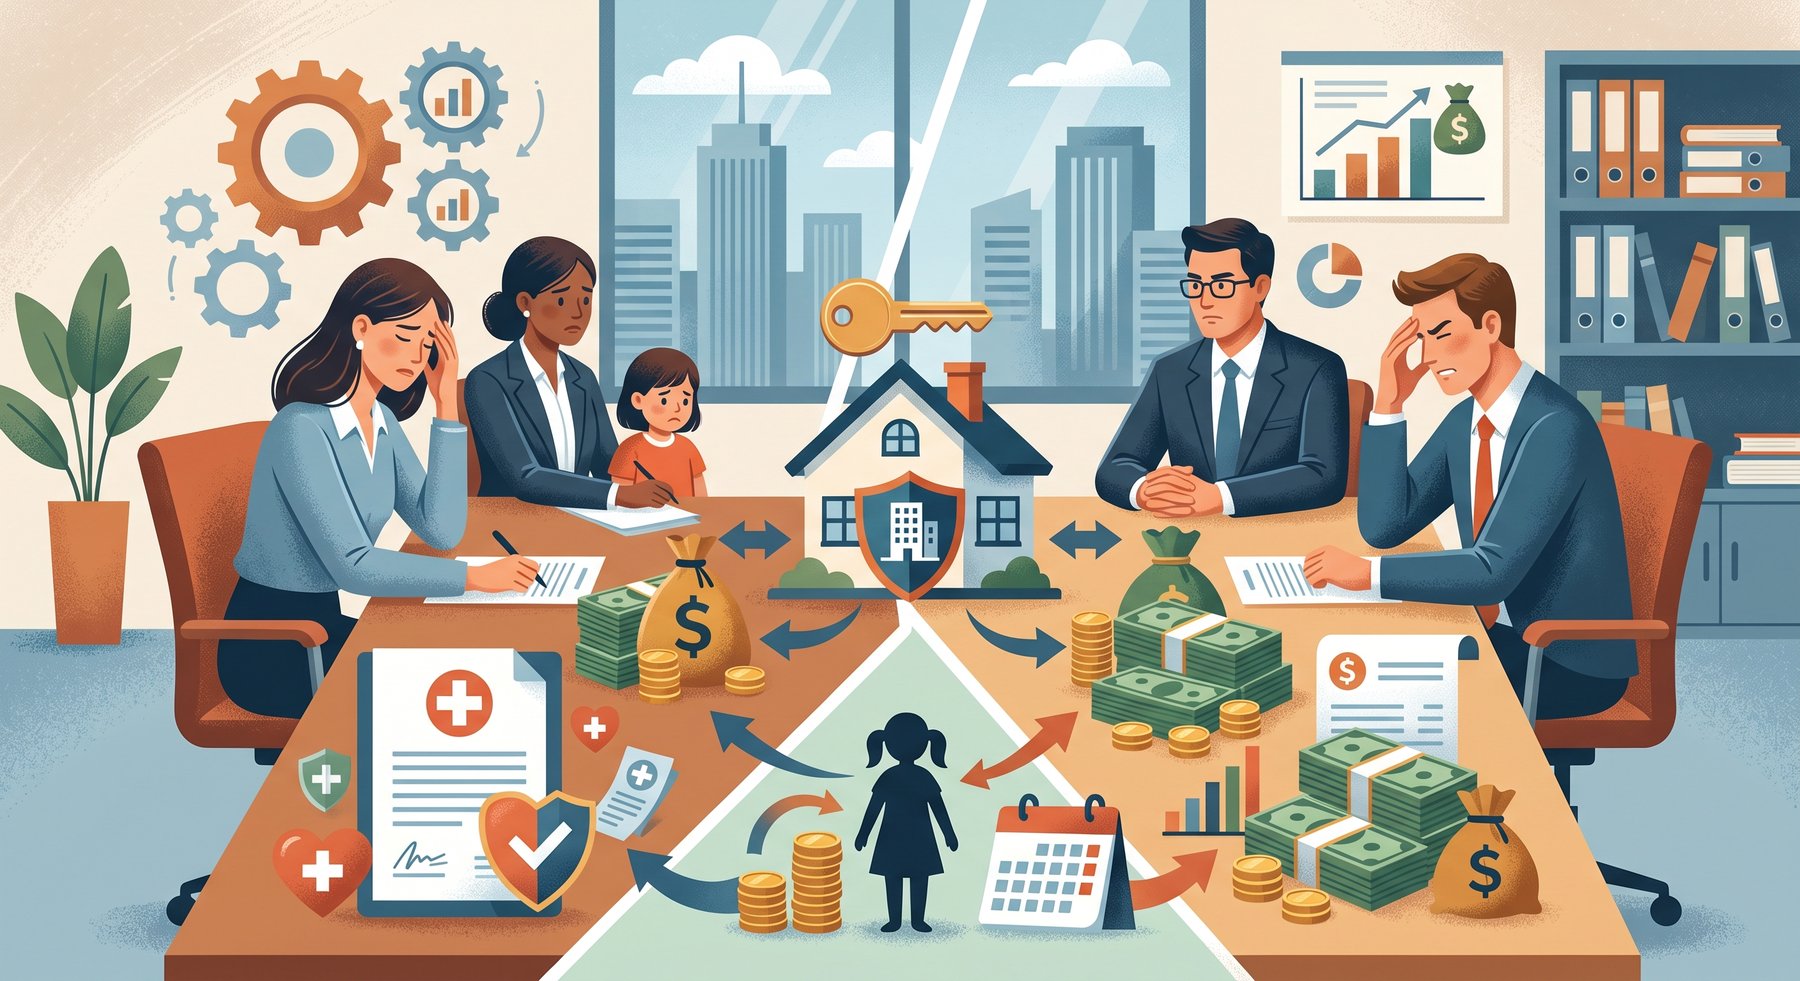
A Tangshan employee of a large industrial enterprise divorces after twenty years of marriage. The family has employer-provided housing rights, deferred bonuses, severance-related compensation, supplemental insurance and a child approaching university age. The spouses disagree over which benefits are property and which are future personal income. The article distinguishes vested property rights, contingent employment benefits and current income used for support.
Employment benefits have to be unpacked before they can be divided. Employment benefits have to be unpacked before they can be divided. Salary, bonus, housing, insurance and compensation should not be treated as one package. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are insurance and pension records, restructuring notices and bonus plans. [1][2]
The specific problem
The Legal Rule
A Tangshan employee of a large industrial enterprise divorces after twenty years of marriage.
The Business Impact
Gather the marriage, identity, asset, income and child-related records that determine jurisdiction and relief before filing or negotiating. Cross-border facts can change both the available order and whether it will be practical to enforce. Apply that to the facts of A Tangshan Divorce Where Employment and Property Overlap: Company Housing, Compensation, Benefits and Child-Support Evidence.
Map each employment benefit to its legal and contractual source
The family-law analysis should therefore follow the benefit’s earning period, payment trigger and transferability. A contingent employment benefit should not be valued as though payment were guaranteed, but it should not disappear from the divorce simply because the employer controls the trigger. The agreement should state when disclosure is due, how tax is handled and when any sharing obligation expires. That keeps the divorce from becoming an indefinite audit of the employee’s career while still protecting the other spouse against concealed later payment. Applied to “Map each employment benefit to its legal and contractual source,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should also show whether map each employment benefit to its legal and contractual source affects current support, future property sharing, or only a disclosure obligation.
Company housing may involve use rights rather than ownership
A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. The decisive question is what legal or contractual right the employee actually holds. Employment terms, purchase options and transfer restrictions determine what can be divided. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are insurance and pension records, HR benefit confirmations and restructuring notices. [1][2]
Employer-controlled rights also require targeted disclosure so the divorce does not become an unnecessary review of the entire personnel file. A contingent employment benefit should not be valued as though payment were guaranteed, but it should not disappear from the divorce simply because the employer controls the trigger. A formula tied to actual future payment can sometimes be fairer than an artificial present valuation. That keeps the divorce from becoming an indefinite audit of the employee’s career while still protecting the other spouse against concealed later payment. Applied to “Company housing may involve use rights rather than ownership,” that produces a section-specific recommendation rather than a reusable evidence checklist.
Deferred bonuses need an earning-period analysis
A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. Work performed during marriage, vesting conditions and payment after separation can create mixed timing questions. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are bonus plans, housing policies and restructuring notices. [1][2]
Vesting conditions and enterprise policy can make two benefits with the same face value economically very different. A contingent employment benefit should not be valued as though payment were guaranteed, but it should not disappear from the divorce simply because the employer controls the trigger. A formula tied to actual future payment can sometimes be fairer than an artificial present valuation. That keeps the divorce from becoming an indefinite audit of the employee’s career while still protecting the other spouse against concealed later payment. Applied to “Deferred bonuses need an earning-period analysis,” that produces a section-specific recommendation rather than a reusable evidence checklist. For deferred bonuses need an earning-period analysis, the employer document should state the vesting or payment condition so the family case does not treat a contingent right as guaranteed cash.
Severance and compensation require component-by-component review
The decisive question is what legal or contractual right the employee actually holds. A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. Wage replacement, statutory compensation and special enterprise benefits may have different characteristics. Employer documents are more informative than broad income labels because company housing, bonus rights and statutory compensation mature differently. The most useful supporting records here are restructuring notices, bonus plans and insurance and pension records. [3]
Employer-controlled rights also require targeted disclosure so the divorce does not become an unnecessary review of the entire personnel file. The settlement can account for uncertainty through later disclosure and a formula tied to actual receipt. A formula tied to actual future payment can sometimes be fairer than an artificial present valuation. That keeps the divorce from becoming an indefinite audit of the employee’s career while still protecting the other spouse against concealed later payment. Applied to “Severance and compensation require component-by-component review,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should also show whether severance and compensation require component-by-component review affects current support, future property sharing, or only a disclosure obligation.
Insurance and welfare benefits should be read from the policy or plan
A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. Cash value, beneficiary rights and contingent future payments differ. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are restructuring notices, employment contracts and insurance and pension records. [4]
The family-law analysis should therefore follow the benefit’s earning period, payment trigger and transferability. A contingent employment benefit should not be valued as though payment were guaranteed, but it should not disappear from the divorce simply because the employer controls the trigger. That approach allows the rest of the divorce to close while contingent employment rights remain properly accounted for. The section should end with a benefit-specific rule for valuation, disclosure or support. Applied to “Insurance and welfare benefits should be read from the policy or plan,” that produces a section-specific recommendation rather than a reusable evidence checklist. For insurance and welfare benefits should be read from the policy or plan, the employer document should state the vesting or payment condition so the family case does not treat a contingent right as guaranteed cash.
Child support needs accurate income evidence without double counting benefits
Employment benefits have to be unpacked before they can be divided. The decisive question is what legal or contractual right the employee actually holds. Cash salary, housing subsidy and reimbursed expenses should be distinguished. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are insurance and pension records, employment contracts and bonus plans. [1][2]
The family-law analysis should therefore follow the benefit’s earning period, payment trigger and transferability. The settlement can account for uncertainty through later disclosure and a formula tied to actual receipt. That approach allows the rest of the divorce to close while contingent employment rights remain properly accounted for. The section should end with a benefit-specific rule for valuation, disclosure or support. Applied to “Child support needs accurate income evidence without double counting benefits,” that produces a section-specific recommendation rather than a reusable evidence checklist. For child support needs accurate income evidence without double counting benefits, the employer document should state the vesting or payment condition so the family case does not treat a contingent right as guaranteed cash.
Employment records may be held by the enterprise rather than either spouse
The decisive question is what legal or contractual right the employee actually holds. The decisive question is what legal or contractual right the employee actually holds. Targeted evidence requests can reduce speculation about benefits. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are bonus plans, employment contracts and HR benefit confirmations. [1][2]
The family-law analysis should therefore follow the benefit’s earning period, payment trigger and transferability. The settlement can account for uncertainty through later disclosure and a formula tied to actual receipt. A formula tied to actual future payment can sometimes be fairer than an artificial present valuation. The section should end with a benefit-specific rule for valuation, disclosure or support. Applied to “Employment records may be held by the enterprise rather than either spouse,” that produces a section-specific recommendation rather than a reusable evidence checklist. For employment records may be held by the enterprise rather than either spouse, the employer document should state the vesting or payment condition so the family case does not treat a contingent right as guaranteed cash.
A job change during divorce can alter both income and housing
A payroll figure alone cannot explain company housing, deferred incentives and restructuring compensation. The decisive question is what legal or contractual right the employee actually holds. Temporary changes should be documented rather than assumed permanent. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are restructuring notices, payroll statements and bonus plans. [3]
Vesting conditions and enterprise policy can make two benefits with the same face value economically very different. A contingent employment benefit should not be valued as though payment were guaranteed, but it should not disappear from the divorce simply because the employer controls the trigger. That approach allows the rest of the divorce to close while contingent employment rights remain properly accounted for. The section should end with a benefit-specific rule for valuation, disclosure or support. Applied to “A job change during divorce can alter both income and housing,” that produces a section-specific recommendation rather than a reusable evidence checklist. The benefit schedule should also show whether a job change during divorce can alter both income and housing affects current support, future property sharing, or only a disclosure obligation.
Deferred employment benefits need a formula before they need a valuation
Employment benefits have to be unpacked before they can be divided. The decisive question is what legal or contractual right the employee actually holds. A deferred bonus or restructuring payment can be uncertain in both amount and timing. The record should identify the source of the benefit and the condition that makes it payable. The most useful supporting records here are employment contracts, payroll statements and housing policies. [1][2]
Vesting conditions and enterprise policy can make two benefits with the same face value economically very different. A contingent employment benefit should not be valued as though payment were guaranteed, but it should not disappear from the divorce simply because the employer controls the trigger. The agreement should state when disclosure is due, how tax is handled and when any sharing obligation expires. The section should end with a benefit-specific rule for valuation, disclosure or support. Applied to “Deferred employment benefits need a formula before they need a valuation,” that produces a section-specific recommendation rather than a reusable evidence checklist. For deferred employment benefits need a formula before they need a valuation, the employer document should state the vesting or payment condition so the family case does not treat a contingent right as guaranteed cash.
Statutory compensation and enterprise benefits should not be collapsed into one number
Employment termination can produce payments with different legal sources. The Labor Contract Law provides statutory economic-compensation rules based on service and wage standards, while an enterprise may also offer contractual bonuses, restructuring incentives, housing assistance or other benefits. A family-law analysis should identify each component before deciding whether and how it is relevant to marital property or current support. [1][3]
Timing is important. Some compensation may relate to employment service accumulated over many years; other payments may be contingent on remaining employed until a future date or on a restructuring plan that has not yet become effective. Payroll and HR documents should show the earning period, payment trigger and any forfeiture condition. If the amount remains genuinely contingent, an agreement based on actual later receipt may be more reliable than a speculative present value.
Tax and social-insurance treatment can also affect the net economic benefit. The Social Insurance Law governs statutory social-insurance rights, while employer supplemental programs may be contractual or policy-based. The spouses do not need to litigate every employment-law issue inside the divorce, but they do need enough information to avoid comparing unlike benefits as if they were the same kind of asset. A precise benefit schedule can therefore improve both support analysis and property settlement. Any future-payment formula should specify the employer document that triggers disclosure and whether the calculation uses gross or net payment.
Company housing and restructuring rights should be valued only after their transferability is understood
An employee’s right to occupy company housing can have substantial practical value to a family even when it is not a freely transferable property right. The first question should be what the enterprise policy or contract actually grants: occupancy linked to employment, a discounted purchase option, a future eligibility right, or an existing ownership interest. Those possibilities have different consequences in divorce. The Civil Code supplies the family-property framework, while the employment or housing arrangement defines what right exists in the first place. [1][2]
The same principle applies to restructuring compensation. A rumored restructuring or internal proposal is not equivalent to an accrued payment. Counsel should identify whether a formal plan exists, what service period or termination event creates entitlement, and whether the payment is statutory compensation under the Labor Contract Law or an additional enterprise benefit. [3] If the amount depends on future employment or a board decision, a present valuation may overstate certainty.
As a drafting response, the spouses can define future disclosure and a sharing formula for a benefit that materializes after divorce. The formula should identify the triggering document, the component of payment covered, tax treatment and an end date for the obligation. This is especially useful where one spouse cannot access the employer’s internal records directly. It allows the divorce to close without forcing the court to value a benefit that may never become payable, while still preventing a later windfall from disappearing outside the agreed settlement. Company housing can also affect support indirectly. A spouse who receives subsidized housing may have lower living costs than the salary figure alone suggests, but that benefit should not automatically be converted into property value. Support analysis should document the actual economic benefit while keeping ownership and future transfer questions separate.
Case study: applying the framework
Assume the employee has a company apartment subject to a future purchase option, a RMB 600,000 deferred bonus payable over three years, supplemental pension benefits and a possible restructuring compensation package. The other spouse has lower income and provides most daily care for a seventeen-year-old child.
The company apartment should be analyzed through the enterprise’s housing policy before either spouse treats it as a saleable asset. If the employee holds only a use right with a future purchase option, the current value and transferability may be limited. The deferred bonus requires a different inquiry: what work earned it, what conditions remain, and whether payment can still be lost after divorce. The restructuring compensation may not yet exist at all. A settlement could therefore allocate known property now while requiring later disclosure and a defined sharing formula for a benefit that is earned during marriage but paid only if a future enterprise event occurs.
The employer should not be drawn unnecessarily into the divorce beyond documents needed to explain benefit rights. A targeted request could seek the housing policy, deferred-bonus plan and current compensation statement without demanding unrelated personnel files. If the restructuring package never materializes, the settlement formula should expire cleanly. If it is paid, the employee would provide the payment notice and calculation so the former spouse can verify the agreed share without reopening unrelated property issues. The formula would also state whether tax withholding reduces the amount shared and when supporting payroll documents must be produced. The employer disclosure deadline should be stated.
Suppose the restructuring package is announced after judgment but before the deferred-bonus sharing period ends. The settlement should say whether the two benefits are calculated independently and whether one offsets the other. Employer documentation should control the trigger, and the employee should not be required to disclose unrelated personnel material simply because the enterprise is restructuring. The parties should also define whether any employer tax withholding is deducted before a future shared benefit is calculated and which payroll statement proves the amount received. If a benefit is paid through stock, vouchers or another non-cash form, the agreement should specify the valuation date and the document used to establish value. That valuation rule should apply consistently to any later corrective payment by the employer.
Conclusion
Employment-linked divorce issues require benefit-by-benefit analysis. Company housing, deferred bonuses, statutory compensation and social-insurance rights do not mature on the same terms and should not be valued as if they were interchangeable. Employer documents should establish the right, earning period and trigger; family-law drafting can then decide whether the benefit affects property, support or future disclosure. Formula-based sharing may be more accurate than speculative valuation where payment remains contingent.
Legal and regulatory sources
[1] Civil Code of the People’s Republic of China — [official source](https://www.court.gov.cn/zixun/xiangqing/233181.html) [2] SPC Interpretation on the Marriage and Family Book of the Civil Code (II) — [official source](https://gongbao.court.gov.cn/Details/f1c5234ac6688dfb149449142d53ab.html) [3] Labor Contract Law of the People’s Republic of China — [official source](https://www.npc.gov.cn/zgrdw/npc/xinwen/lfgz/zxfl/2007-06/29/content_368169.htm) [4] Social Insurance Law of the People’s Republic of China — [official source](https://www.npc.gov.cn/zgrdw/npc/xinwen/2019-01/07/content_2070267.htm) [5] Civil Procedure Law of the People’s Republic of China — [official source](https://cicc.court.gov.cn/html/1/218/62/83/443.html)
General legal information only; not legal advice for a specific matter.
Discussion
Share experience or questions about this topic. This is a public discussion — not legal advice. Do not post confidential case details.
Have a question after reading? Leave it here, or Ask a Lawyer for a free initial intake.
Comments are moderated. China Legal Portal is a directory and information resource; no attorney–client relationship is formed by posting here.