Understanding the WFOE Structure
The Legal Rule
In China, treat establishing a wholly foreign-owned enterprise as a question of a step-by-step legal guide. Naming the city does not replace the papers, approvals or forum that actually control the outcome.
The Business Impact
In China, confirm the documents, authority and local filings for this establishing a wholly foreign-owned enterprise matter before you pay, transfer or sue. The city name is not a substitute for the file.
The Wholly Foreign-Owned Enterprise (WFOE) remains the most popular corporate vehicle for foreign investors seeking to establish a substantive business presence in China. Unlike a representative office, a WFOE can directly engage in revenue-generating activities, hire employees, issue invoices, and repatriate profits.
- Full Control — The foreign investor retains 100% ownership
- Direct Billing — Issue RMB-denominated invoices
- Employment — Direct hiring under Chinese labor law
- Profit Repatriation — Legal remittance of after-tax profits
The Foreign Investment Negative List
Foreign investors must consult the current Negative List, which specifies industries where foreign ownership is restricted. Manufacturing, software development, and professional services are generally open to 100% foreign ownership, while media, telecom, and education face restrictions.
Under the Foreign Investment Law, foreign-invested enterprises enjoy national treatment, subject to the same requirements as domestic companies except where restricted by the Negative List.
Registration Procedure
The incorporation process includes name pre-approval (1-3 days), articles of association notarization (2-5 days), business license application (5-10 days), company seal carving (1-2 days), tax registration (immediate), foreign exchange registration (5 days), and bank account opening (3-5 days).
Capital Considerations
China abolished minimum registered capital for most industries in 2014, moving to a subscribed capital system. The amount signals financial commitment and affects visa applications, bank financing, and government procurement eligibility.
Post-Establishment Obligations
Annual reports must be submitted between January 1 and June 30. Monthly or quarterly tax filings are required, and all cross-border capital movements must go through designated foreign exchange banks.
'Tax Considerations for WFOE Operations
Foreign-invested enterprises in China are subject to a comprehensive tax framework that requires careful planning. The standard corporate income tax rate is 25 percent, though certain industries and regions qualify for reduced rates. Small and micro enterprises with annual taxable income below RMB 3 million may benefit from preferential rates as low as 5 percent on the first RMB 1 million and 10 percent on the remainder. Value-added tax applies to most business activities, with general taxpayers facing rates of 13 percent for goods, 9 percent for services, and 6 percent for certain modern service industries.

- FAILURE MODES
- Negative list; FI information report
- Constitution
Withholding tax on dividends paid to foreign shareholders is typically 10 percent, though this may be reduced under applicable double taxation treaties. China has an extensive network of tax treaties with over 100 countries that can significantly reduce withholding rates. For example, dividends paid to a parent company in Singapore may qualify for a reduced rate of 5 percent if certain conditions are met. Royalties and interest payments to foreign entities are also subject to withholding tax, typically at 10 percent but reducible under treaty provisions.
Transfer Pricing Compliance
China\’s tax authorities actively scrutinize related-party transactions through transfer pricing audits. Foreign-invested enterprises must maintain contemporaneous documentation demonstrating that their intercompany transactions comply with the arm\’s length principle. Annual related-party transaction reporting is mandatory through the Corporate Income Tax return, and enterprises meeting certain thresholds must prepare a transfer pricing documentation package including a master file, local file, and country-by-country report.
The State Taxation Administration has increased its focus on service transactions, intangible property transfers, and financing arrangements between related parties. Management service fees, technical service fees, and royalty payments are particularly susceptible to adjustment. Tax authorities may impose adjustments with interest and penalties if they determine that pricing does not reflect market conditions.
Labor and Employment Compliance
WFOEs employing staff in China must navigate the comprehensive Chinese labor law framework. Employment contracts are mandatory and must be in writing, containing specific terms including job description, compensation, working hours, social insurance, and termination provisions. Fixed-term contracts are the most common, and after two consecutive fixed-term contracts or ten years of service with the same employer, the employee is entitled to request an open-term contract.
Social insurance contributions represent a significant employment cost. Employers must contribute to pension, medical, unemployment, work injury, and maternity insurance pools, totaling approximately 30 to 35 percent of each employee\’s salary. The exact rates vary by city. Housing fund contributions add an additional 5 to 12 percent on both employer and employee sides. Foreign employees working in China are generally required to participate in the social insurance system.
Annual Compliance Calendar
WFOEs must adhere to a strict annual compliance calendar. Key obligations include: annual enterprise information report filing by June 30, annual corporate income tax reconciliation by May 31, foreign exchange annual reporting by June 30, and the annual audit by a licensed Chinese CPA firm. Failure to meet these deadlines can result in fines, enhanced regulatory scrutiny, and adverse credit records.
For a comprehensive assessment of your specific investment plans and compliance needs, contact our firm to schedule a consultation with our foreign investment team in Shenyang.
'''Common Pitfalls in WFOE Registration
First-time foreign investors frequently encounter several common pitfalls during the WFOE registration process. One of the most significant challenges is underestimating the time required for business scope definition. The business scope, which must be stated in the company’s articles of association and business license, must be carefully worded to capture the company’s intended activities without being too broad. Overly broad business scopes may be rejected during examination, while overly narrow scopes may prevent the company from engaging in necessary business activities. Post-registration changes to the business scope require a formal amendment process that takes additional time and incurs government fees.
Another frequent issue involves the verification of registered capital contribution. While China does not require capital to be paid in full at incorporation, the subscribed capital must be contributed within the timeframe stated in the company’s articles of association. Foreign investors sometimes mistake the subscribed capital for a mere formality, only to face complications when the capital contribution deadline approaches. Failure to contribute subscribed capital on time can result in fines, restrictions on corporate changes, and potential personal liability for directors.

- Establishing a Wholly Foreign-Owned Enterprise in China — process.
- List-check the scope
- File SAMR / FI report
- Open bank / SAFE
- Inject capital on time
Lease agreements for the registered office address present another challenge. Chinese law requires WFOEs to have a physical office address, and the lease agreement must be registered with the local housing authority. Some landlords are unwilling to register the lease for tax reasons, which creates an obstacle to business license issuance. Foreign investors should verify that their proposed landlord is willing and able to provide the documentation needed for registration before signing a lease.
Bank Account Opening for WFOEs
Opening bank accounts for a newly established WFOE requires careful planning. The company needs both a basic account for daily operations and a capital account for foreign currency transactions. The capital account is required for receiving the initial capital injection from the foreign parent company and for repatriating profits and dividends. Bank account opening procedures have become more stringent in recent years, with banks requiring extensive documentation to comply with anti-money laundering and foreign exchange control regulations.
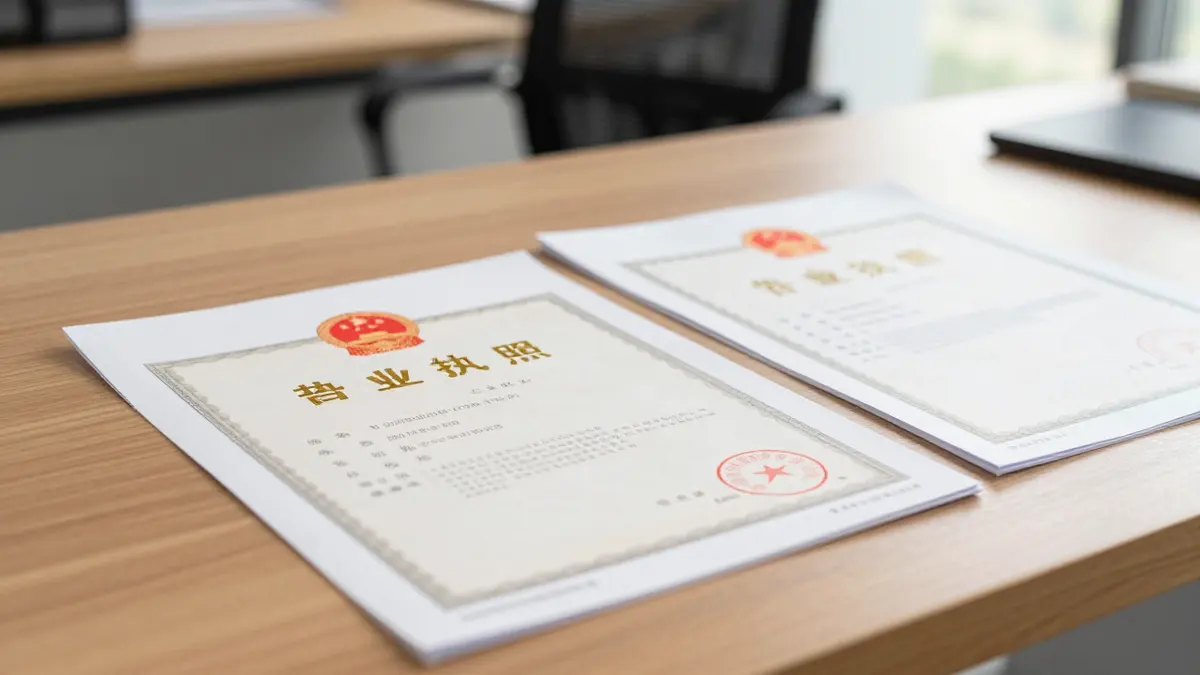
Banks typically require the following documents: the original business license, the company’s articles of association and seal registration certificate, the legal representative’s passport or ID card and proof of address, the company’s business scope and anticipated transaction volume, and board resolutions authorizing account opening. The process from application to final account activation may take one to three weeks depending on the bank and the completeness of documentation.
Discussion
Share experience or questions about this topic. This is a public discussion — not legal advice. Do not post confidential case details.
Have a question after reading? Leave it here, or Ask a Lawyer for a free initial intake.
Comments are moderated. China Legal Portal is a directory and information resource; no attorney–client relationship is formed by posting here.