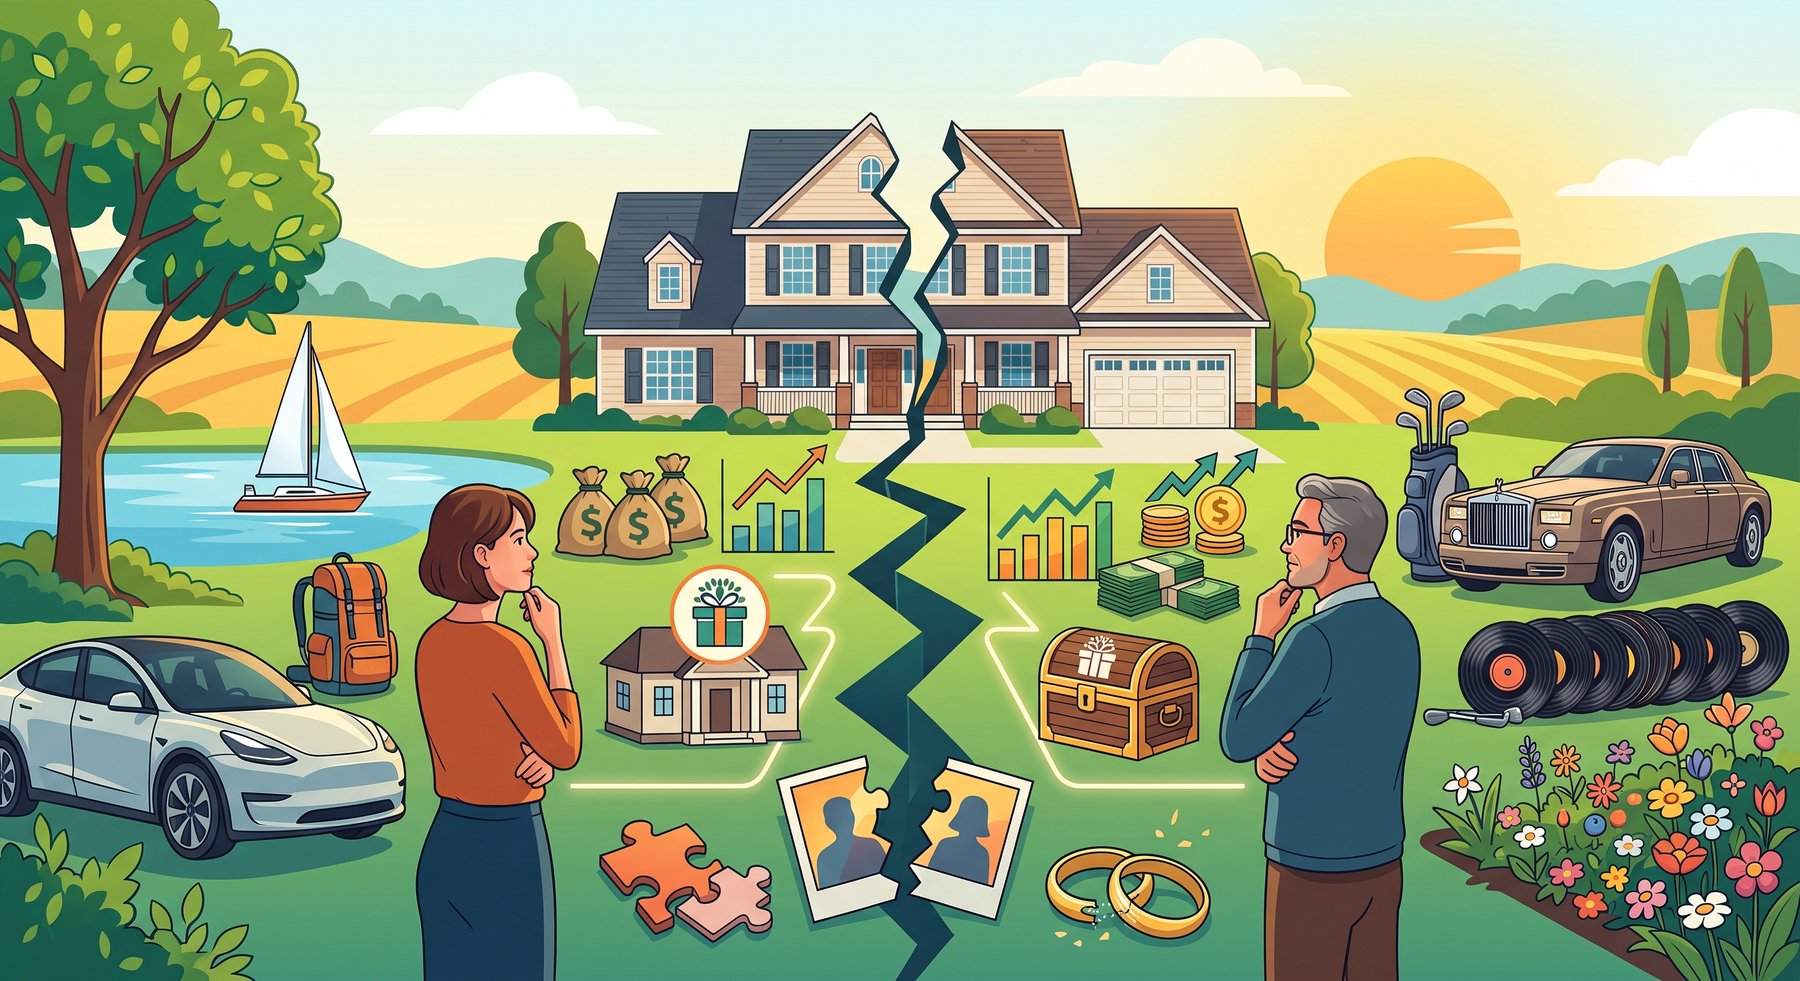
A Tangshan couple has lived separately for six years before filing for divorce. During that period one spouse inherited property, both opened separate investment accounts, the family home appreciated substantially, and one spouse says several post-separation purchases were made entirely from personal income. The years of separation change the tracing problem but do not create an automatic statutory cut-off for marital property.
Six years of living apart makes chronology more important, not less. This issue is best understood by tracing the asset forward from acquisition rather than labeling everything by the date of divorce. The legal status of the marriage and source of each acquisition still need evidence. A long-separation dispute becomes manageable when the lawyer follows significant assets and transfers instead of trying to recreate every household expense. The most useful supporting records here are tax and registration documents, mortgage records and inheritance documents. [1][2]
The specific problem
The Legal Rule
In Tangshan, treat divorce after years of separation as a question of post-separation assets, inheritance and the evidence needed to reconstruct the marital estate. Naming the city does not replace the papers, approvals or forum that actually control the outcome.
The Business Impact
In Tangshan, confirm the documents, authority and local filings for this divorce after years of separation matter before you pay, transfer or sue. The city name is not a substitute for the file.
Long separation does not itself replace the marital-property rules
Inheritance and later reinvestment are especially sensitive to tracing because an initially personal asset can move through several forms. Physical separation can explain why accounts and spending diverged, but it does not itself decide the legal character of later acquisitions. Where perfect tracing is no longer possible, a negotiated credit may be more proportionate than years of forensic accounting. That allows the parties to spend litigation resources on transactions that actually change the final division. Applied to “Long separation does not itself replace the marital-property rules,” that produces a section-specific recommendation rather than a reusable evidence checklist.
Build an asset timeline around the date and source of each purchase
This issue is best understood by tracing the asset forward from acquisition rather than labeling everything by the date of divorce. The asset history should be reconstructed from the point at which the spouses’ financial lives began to diverge. Bank statements, contracts, inheritance documents and sale proceeds should be linked. The evidence should answer whether the asset remained identifiable through years of separate financial activity. The most useful supporting records here are mortgage records, tax and registration documents and property-sale contracts. [1][2]
A long-separation case therefore rewards selective reconstruction of transactions that materially change classification or value. Physical separation can explain why accounts and spending diverged, but it does not itself decide the legal character of later acquisitions. The settlement can use a practical ledger without pretending that physical separation created a new legal property regime. The useful endpoint is a traceable value, a defined evidentiary uncertainty or a negotiated credit. Applied to “Build an asset timeline around the date and source of each purchase,” that produces a section-specific recommendation rather than a reusable evidence checklist. For build an asset timeline around the date and source of each purchase, the tracing schedule should show the last point at which the source remains identifiable and the value still reasonably attributable to it.
Inheritance requires attention to the instrument and later mixing
Six years of living apart makes chronology more important, not less. Six years of living apart makes chronology more important, not less. Will terms, statutory inheritance, account commingling and reinvestment can change the factual problem. A long-separation dispute becomes manageable when the lawyer follows significant assets and transfers instead of trying to recreate every household expense. The most useful supporting records here are securities statements, mortgage records and property-sale contracts. [1][2]
A long-separation case therefore rewards selective reconstruction of transactions that materially change classification or value. Physical separation can explain why accounts and spending diverged, but it does not itself decide the legal character of later acquisitions. Where perfect tracing is no longer possible, a negotiated credit may be more proportionate than years of forensic accounting. The useful endpoint is a traceable value, a defined evidentiary uncertainty or a negotiated credit. Applied to “Inheritance requires attention to the instrument and later mixing,” that produces a section-specific recommendation rather than a reusable evidence checklist. For inheritance requires attention to the instrument and later mixing, the tracing schedule should show the last point at which the source remains identifiable and the value still reasonably attributable to it.
Separate accounts are not automatically separate property
Six years of living apart makes chronology more important, not less. The asset history should be reconstructed from the point at which the spouses’ financial lives began to diverge. Account title should be distinguished from the source of funds and transactions inside it. The evidence should answer whether the asset remained identifiable through years of separate financial activity. The most useful supporting records here are tax and registration documents, salary accounts and mortgage records. [1][2]
Separate accounts and separate households can change the evidence while the statutory marital-property rules continue to govern. Inheritance, sale proceeds and mixed accounts therefore require transaction tracing rather than assumptions based on who held the account. The settlement can use a practical ledger without pretending that physical separation created a new legal property regime. That allows the parties to spend litigation resources on transactions that actually change the final division. Applied to “Separate accounts are not automatically separate property,” that produces a section-specific recommendation rather than a reusable evidence checklist. For separate accounts are not automatically separate property, the tracing schedule should show the last point at which the source remains identifiable and the value still reasonably attributable to it.
Appreciation of the family home needs a practical division method
Six years of living apart makes chronology more important, not less. This issue is best understood by tracing the asset forward from acquisition rather than labeling everything by the date of divorce. Ownership, mortgage, renovation and market growth should be separated. The evidence should answer whether the asset remained identifiable through years of separate financial activity. The most useful supporting records here are securities statements, inheritance documents and tax and registration documents. [1][3]
A long-separation case therefore rewards selective reconstruction of transactions that materially change classification or value. Inheritance, sale proceeds and mixed accounts therefore require transaction tracing rather than assumptions based on who held the account. The settlement can use a practical ledger without pretending that physical separation created a new legal property regime. That allows the parties to spend litigation resources on transactions that actually change the final division. Applied to “Appreciation of the family home needs a practical division method,” that produces a section-specific recommendation rather than a reusable evidence checklist. The separation timeline should distinguish appreciation of the family home needs a practical division method from ordinary post-separation living expenses that do not materially change the asset classification.
Post-separation income and expenses can complicate fairness arguments
This issue is best understood by tracing the asset forward from acquisition rather than labeling everything by the date of divorce. Six years of living apart makes chronology more important, not less. Support, mortgage payments and family expenses should be recorded without inventing a legal separation regime. A long-separation dispute becomes manageable when the lawyer follows significant assets and transfers instead of trying to recreate every household expense. The most useful supporting records here are tax and registration documents, property-sale contracts and securities statements. [1][3]
Separate accounts and separate households can change the evidence while the statutory marital-property rules continue to govern. Inheritance, sale proceeds and mixed accounts therefore require transaction tracing rather than assumptions based on who held the account. The aim is to resolve the assets that matter, not to recreate every household expense over six years. That allows the parties to spend litigation resources on transactions that actually change the final division. Applied to “Post-separation income and expenses can complicate fairness arguments,” that produces a section-specific recommendation rather than a reusable evidence checklist. The separation timeline should distinguish post-separation income and expenses can complicate fairness arguments from ordinary post-separation living expenses that do not materially change the asset classification.
Transfers between relatives deserve transaction-level proof
The asset history should be reconstructed from the point at which the spouses’ financial lives began to diverge. Six years of living apart makes chronology more important, not less. Repayment, gift, investment and concealment should be distinguished. A long-separation dispute becomes manageable when the lawyer follows significant assets and transfers instead of trying to recreate every household expense. The most useful supporting records here are securities statements, inheritance documents and family-transfer records. [1][3]
A long-separation case therefore rewards selective reconstruction of transactions that materially change classification or value. Physical separation can explain why accounts and spending diverged, but it does not itself decide the legal character of later acquisitions. Where perfect tracing is no longer possible, a negotiated credit may be more proportionate than years of forensic accounting. The useful endpoint is a traceable value, a defined evidentiary uncertainty or a negotiated credit. Applied to “Transfers between relatives deserve transaction-level proof,” that produces a section-specific recommendation rather than a reusable evidence checklist. The separation timeline should distinguish transfers between relatives deserve transaction-level proof from ordinary post-separation living expenses that do not materially change the asset classification.
Preservation should focus on assets that can actually move
The asset history should be reconstructed from the point at which the spouses’ financial lives began to diverge. The asset history should be reconstructed from the point at which the spouses’ financial lives began to diverge. Investment accounts and sale proceeds may need faster attention than registered real estate. The evidence should answer whether the asset remained identifiable through years of separate financial activity. The most useful supporting records here are family-transfer records, inheritance documents and securities statements. [1][2]
Inheritance and later reinvestment are especially sensitive to tracing because an initially personal asset can move through several forms. Inheritance, sale proceeds and mixed accounts therefore require transaction tracing rather than assumptions based on who held the account. The settlement can use a practical ledger without pretending that physical separation created a new legal property regime. That allows the parties to spend litigation resources on transactions that actually change the final division. Applied to “Preservation should focus on assets that can actually move,” that produces a section-specific recommendation rather than a reusable evidence checklist. The separation timeline should distinguish preservation should focus on assets that can actually move from ordinary post-separation living expenses that do not materially change the asset classification.
Settlement can use a cut-off ledger without changing the governing law
This issue is best understood by tracing the asset forward from acquisition rather than labeling everything by the date of divorce. Six years of living apart makes chronology more important, not less. The parties may agree how to treat later earnings and spending to reduce accounting disputes. A long-separation dispute becomes manageable when the lawyer follows significant assets and transfers instead of trying to recreate every household expense. The most useful supporting records here are family-transfer records, salary accounts and tax and registration documents. [1][3]
A long-separation case therefore rewards selective reconstruction of transactions that materially change classification or value. Inheritance, sale proceeds and mixed accounts therefore require transaction tracing rather than assumptions based on who held the account. The settlement can use a practical ledger without pretending that physical separation created a new legal property regime. The useful endpoint is a traceable value, a defined evidentiary uncertainty or a negotiated credit. Applied to “Settlement can use a cut-off ledger without changing the governing law,” that produces a section-specific recommendation rather than a reusable evidence checklist. For settlement can use a cut-off ledger without changing the governing law, the tracing schedule should show the last point at which the source remains identifiable and the value still reasonably attributable to it.
A long separation calls for a selective rather than exhaustive tracing strategy
Six years of separate financial activity can produce thousands of transactions. Attempting to reconstruct every purchase and household expense may cost more than the disputed value and can distract from legally significant assets. The lawyer should rank transactions by potential effect on classification and value: inheritance, sale of registered property, large transfers, securities accounts, major debt and acquisitions that replaced earlier assets. Ordinary consumption generally requires a different level of attention. [1][2][3]
This prioritization is not an excuse to ignore inconvenient records. If one spouse claims that a current investment account derives from inherited property, the sale proceeds and subsequent transfers must be traced far enough to test that claim. If the funds became heavily mixed with salary and repeated withdrawals, the evidentiary uncertainty should be stated honestly. The parties can then decide whether litigation over the tracing problem is proportionate.
A negotiated ledger can be particularly useful where both spouses incurred substantial post-separation expenses. They may agree to credit mortgage payments, school costs or a small number of major family expenses without asking the court to recreate a statutory separation date that does not exist. This is a settlement device, not a statement that physical separation changes the governing property regime. Used carefully, it can reduce the accounting burden while preserving the legal treatment of inheritance and other significant assets. The spouses can also define how market gains or losses after the agreed valuation date are treated until securities or property are actually transferred.
Mixed accounts should be traced by source and replacement asset, not by account title
A separate investment account opened during a long separation may contain several categories of value: salary earned during the marriage, proceeds from inherited property, dividends, sale proceeds and market gains. The account being in one spouse’s name does not answer the family-law question. Counsel should identify significant inflows and follow them into current holdings where possible. The Civil Code’s rules on marital and personal property, together with the current marriage-family interpretations, provide the legal framework; the factual challenge is preserving the source history after years of transactions. [1][2]
Tracing should be proportionate. If inherited apartment proceeds entered the account once and can be followed into a particular investment, the evidentiary task may be straightforward. If the account received monthly salary, repeated withdrawals and dozens of trades, precise tracing may become costly and uncertain. The lawyer should state that uncertainty openly and identify which legal conclusion actually depends on resolving it. Not every gain or loss over six years justifies expert reconstruction.
A settlement can use a negotiated credit or agreed tracing methodology without claiming that the law mandates that compromise. For example, the spouses may accept a fixed value for the identifiable inherited contribution and divide the remaining account under an agreed formula. That can be more efficient than litigating every trade while still respecting the principle that an inheritance intended for one spouse may begin as personal property. The key is to distinguish the negotiated method from the substantive rule.
Market appreciation should also be separated from traceable principal. If an inherited asset is sold and the proceeds are invested, the dispute may concern both whether the principal remained identifiable and how later gains are treated. A settlement can distinguish those components explicitly rather than using the current account balance as a single proxy for both source and growth.
Case study: applying the framework
Assume the husband inherited a Tangshan apartment from his father in year two of separation and later sold it, placing the proceeds into an investment account that also received salary. The wife paid the family-home mortgage and school costs during most of the six years.
The inherited apartment presents a tracing problem because sale proceeds were later mixed with salary. The lawyer would identify the sale contract, original inheritance document, transfer into the investment account and subsequent withdrawals. If the account then funded a jointly used asset, that later transaction would need separate analysis. The wife’s mortgage and school payments during separation should also be documented because they may be relevant to negotiation and reimbursement even though long physical separation does not create a new statutory property regime by itself. A practical settlement could use an agreed cut-off ledger for later income and expenses while preserving the legal classification of the inheritance and family home.
A settlement ledger could then separate three categories: inherited value that remains traceable, marital value in the family home, and post-separation spending the spouses agree to credit for practical settlement purposes. That ledger would not create a new legal regime for the years of separation, but it could reduce evidentiary disputes about later transactions. If the investment account contains mixed funds, the parties could agree a tracing method or negotiate a fixed credit rather than litigating every trade. The parties could also agree how investment gains or losses after the settlement cut-off are allocated until transfers are completed. Where records from early years are unavailable, counsel should distinguish genuine evidentiary gaps from adverse inferences and consider whether a negotiated credit is more proportionate than extended tracing litigation.
If the investment account has become too mixed for precise tracing, the spouses could ask an expert to identify only the major inherited inflow and the current securities reasonably linked to it. The remaining account can then be negotiated separately. That targeted approach gives the court a concrete evidentiary question instead of an open-ended six-year reconstruction. Where valuation dates differ across assets, the settlement should state them expressly so later market movement is not mistaken for a tracing dispute.
Conclusion
Years of separation create a tracing challenge, not an automatic new property regime. The useful strategy is to follow inheritance, major acquisitions, registered property and substantial transfers while avoiding an expensive attempt to reconstruct every ordinary expense. Where tracing becomes uncertain, the uncertainty should be stated rather than hidden. A negotiated cut-off ledger or credit can resolve practical post-separation contributions without changing the legal character of inherited or marital assets.
Legal and regulatory sources
[1] Civil Code of the People’s Republic of China — [official source](https://www.court.gov.cn/zixun/xiangqing/233181.html) [2] SPC Interpretation on the Marriage and Family Book of the Civil Code (II) — [official source](https://gongbao.court.gov.cn/Details/f1c5234ac6688dfb149449142d53ab.html) [3] Civil Procedure Law of the People’s Republic of China — [official source](https://cicc.court.gov.cn/html/1/218/62/83/443.html)
General legal information only; not legal advice for a specific matter.
Discussion
Share experience or questions about this topic. This is a public discussion — not legal advice. Do not post confidential case details.
Have a question after reading? Leave it here, or Ask a Lawyer for a free initial intake.
Comments are moderated. China Legal Portal is a directory and information resource; no attorney–client relationship is formed by posting here.