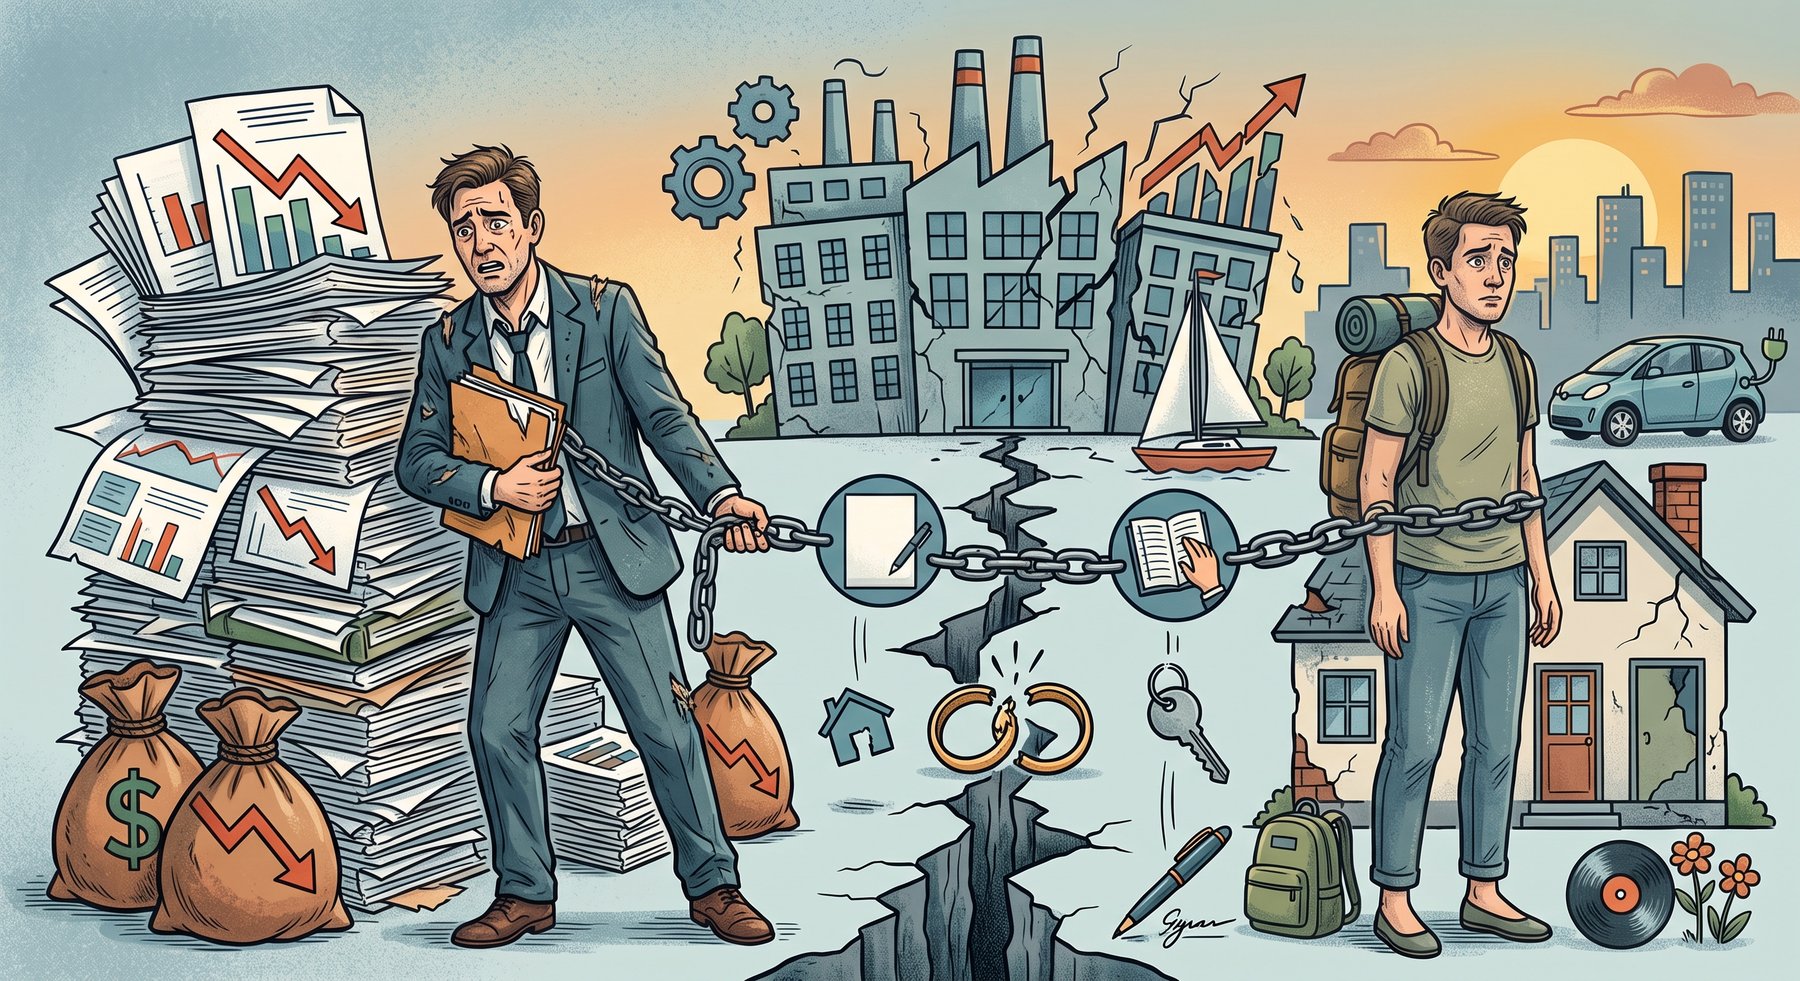
A Shijiazhuang entrepreneur and spouse divorce while the entrepreneur’s company owes suppliers and banks. The entrepreneur also signed personal guarantees, used a joint household account for some business expenses and borrowed money from a friend. The other spouse argues that all business debt should stay with the entrepreneur. Existing preservation or enforcement against the entrepreneur can reduce the liquid assets available for family settlement. Counsel should therefore check current creditor actions before proposing an allocation that depends on funds already exposed to third-party claims. The central task is to distinguish company borrowing, personal guarantees and true marital debt before creditor enforcement reshapes the family balance sheet.
This issue begins with the contract and use of funds, not with the fact that the family owns the business. The company, the entrepreneur and the marital community can sit around the same transaction without sharing identical liability. Three legal relationships can coexist around the same business. The debt should be traced from creditor to borrower to actual use of funds before it enters the marital balance sheet. The most useful supporting records here are guarantees, enforcement records and loan agreements. [1][2]
The specific problem
The Legal Rule
A Shijiazhuang entrepreneur and spouse divorce while the entrepreneur’s company owes suppliers and banks.
The Business Impact
Gather the marriage, identity, asset, income and child-related records that determine jurisdiction and relief before filing or negotiating. Cross-border facts can change both the available order and whether it will be practical to enforce. Apply that to the facts of When Business Debt Enters a Shijiazhuang Divorce: Distinguishing Joint Marital Debt, Personal Debt and Company Obligations.
Separate company debt, personal guarantees and marital debt
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. A spouse’s internal promise to bear a debt does not release a creditor, and company assets do not become marital property simply because the family owns shares. The agreement should therefore model what happens if the company defaults or a guarantee is enforced. Security or reserves may be needed where the settlement depends on assets that a creditor can reach before the equalization is paid. Applied to “Separate company debt, personal guarantees and marital debt,” that produces a section-specific recommendation rather than a reusable evidence checklist.
The purpose of borrowing matters to marital-liability analysis
Business debt should be sorted by debtor before it is sorted between spouses. The company, the entrepreneur and the marital community can sit around the same transaction without sharing identical liability. Household use, business use and one spouse’s personal use should be traced. The debt should be traced from creditor to borrower to actual use of funds before it enters the marital balance sheet. The most useful supporting records here are shareholder documents, enforcement records and loan agreements. [1][2]
Current enforcement risk also affects the practical value of any family settlement based on liquid assets. A spouse’s internal promise to bear a debt does not release a creditor, and company assets do not become marital property simply because the family owns shares. Indemnity without security may offer little protection where the business is already distressed. The section should finish with the external enforcement risk and the internal allocation between spouses stated separately. Applied to “The purpose of borrowing matters to marital-liability analysis,” that produces a section-specific recommendation rather than a reusable evidence checklist. The settlement model should show how the purpose of borrowing matters to marital-liability analysis affects creditor exposure before liquid family assets are distributed.
A company creditor is not automatically a creditor of the spouse
Business debt should be sorted by debtor before it is sorted between spouses. Business debt should be sorted by debtor before it is sorted between spouses. Corporate personality and guarantee documents should be respected. Company borrowing, a personal guarantee and a household-account transfer can arise from one business problem while creating different liabilities. The most useful supporting records here are shareholder documents, company ledgers and joint-account statements. [1][2]
Current enforcement risk also affects the practical value of any family settlement based on liquid assets. The Civil Code joint-debt framework and company personality should remain separate in the analysis. Indemnity without security may offer little protection where the business is already distressed. Security or reserves may be needed where the settlement depends on assets that a creditor can reach before the equalization is paid. Applied to “A company creditor is not automatically a creditor of the spouse,” that produces a section-specific recommendation rather than a reusable evidence checklist. For a company creditor is not automatically a creditor of the spouse, the liability matrix should separate the company’s obligation, any personal guarantee and the evidence said to make the debt marital.
Personal guarantees need contract-level review
Business debt should be sorted by debtor before it is sorted between spouses. Business debt should be sorted by debtor before it is sorted between spouses. Scope, amount, trigger and whether the other spouse signed or benefited should be identified. Company borrowing, a personal guarantee and a household-account transfer can arise from one business problem while creating different liabilities. The most useful supporting records here are supplier claims, shareholder documents and loan agreements. [1][2]
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. The Civil Code joint-debt framework and company personality should remain separate in the analysis. The objective is to divide family value with a realistic view of third-party creditor claims. The section should finish with the external enforcement risk and the internal allocation between spouses stated separately. Applied to “Personal guarantees need contract-level review,” that produces a section-specific recommendation rather than a reusable evidence checklist. The settlement model should show how personal guarantees need contract-level review affects creditor exposure before liquid family assets are distributed.
Household accounts can contain both family and business flows
Business debt should be sorted by debtor before it is sorted between spouses. This issue begins with the contract and use of funds, not with the fact that the family owns the business. Bank tracing should separate transfers rather than label the whole account. The debt should be traced from creditor to borrower to actual use of funds before it enters the marital balance sheet. The most useful supporting records here are guarantees, supplier claims and company ledgers. [1][4]
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. The Civil Code joint-debt framework and company personality should remain separate in the analysis. The agreement should therefore model what happens if the company defaults or a guarantee is enforced. Security or reserves may be needed where the settlement depends on assets that a creditor can reach before the equalization is paid. Applied to “Household accounts can contain both family and business flows,” that produces a section-specific recommendation rather than a reusable evidence checklist. For household accounts can contain both family and business flows, the liability matrix should separate the company’s obligation, any personal guarantee and the evidence said to make the debt marital.
The spouse’s knowledge and consent can be evidentially important
Business debt should be sorted by debtor before it is sorted between spouses. This issue begins with the contract and use of funds, not with the fact that the family owns the business. Communications and participation should be examined without assuming silence equals agreement. Company borrowing, a personal guarantee and a household-account transfer can arise from one business problem while creating different liabilities. The most useful supporting records here are supplier claims, joint-account statements and enforcement records. [1][4]
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. The Civil Code joint-debt framework and company personality should remain separate in the analysis. The agreement should therefore model what happens if the company defaults or a guarantee is enforced. Security or reserves may be needed where the settlement depends on assets that a creditor can reach before the equalization is paid. Applied to “The spouse’s knowledge and consent can be evidentially important,” that produces a section-specific recommendation rather than a reusable evidence checklist. The settlement model should show how the spouse’s knowledge and consent can be evidentially important affects creditor exposure before liquid family assets are distributed.
Business assets should not be confused with marital property
This issue begins with the contract and use of funds, not with the fact that the family owns the business. The company, the entrepreneur and the marital community can sit around the same transaction without sharing identical liability. Company inventory and receivables belong to the company even if shares are marital. Company borrowing, a personal guarantee and a household-account transfer can arise from one business problem while creating different liabilities. The most useful supporting records here are loan agreements, joint-account statements and company ledgers. [1][3]
Mixed household accounts require transaction tracing because account title cannot convert company money into marital debt automatically. The Civil Code joint-debt framework and company personality should remain separate in the analysis. The agreement should therefore model what happens if the company defaults or a guarantee is enforced. Security or reserves may be needed where the settlement depends on assets that a creditor can reach before the equalization is paid. Applied to “Business assets should not be confused with marital property,” that produces a section-specific recommendation rather than a reusable evidence checklist. For business assets should not be confused with marital property, the liability matrix should separate the company’s obligation, any personal guarantee and the evidence said to make the debt marital.
Creditor actions during divorce can affect preservation and settlement
This issue begins with the contract and use of funds, not with the fact that the family owns the business. Business debt should be sorted by debtor before it is sorted between spouses. Existing enforcement risk should be mapped before asset division. Company borrowing, a personal guarantee and a household-account transfer can arise from one business problem while creating different liabilities. The most useful supporting records here are company ledgers, enforcement records and shareholder documents. [1][2]
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. A spouse’s internal promise to bear a debt does not release a creditor, and company assets do not become marital property simply because the family owns shares. Indemnity without security may offer little protection where the business is already distressed. Security or reserves may be needed where the settlement depends on assets that a creditor can reach before the equalization is paid. Applied to “Creditor actions during divorce can affect preservation and settlement,” that produces a section-specific recommendation rather than a reusable evidence checklist.
A divorce agreement cannot eliminate third-party creditor rights
This issue begins with the contract and use of funds, not with the fact that the family owns the business. This issue begins with the contract and use of funds, not with the fact that the family owns the business. Internal allocation needs security or indemnity if external liability remains. Company borrowing, a personal guarantee and a household-account transfer can arise from one business problem while creating different liabilities. The most useful supporting records here are shareholder documents, joint-account statements and enforcement records. [1][2]
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. The Civil Code joint-debt framework and company personality should remain separate in the analysis. The agreement should therefore model what happens if the company defaults or a guarantee is enforced. The section should finish with the external enforcement risk and the internal allocation between spouses stated separately. Applied to “A divorce agreement cannot eliminate third-party creditor rights,” that produces a section-specific recommendation rather than a reusable evidence checklist. For a divorce agreement cannot eliminate third-party creditor rights, the liability matrix should separate the company’s obligation, any personal guarantee and the evidence said to make the debt marital.
Settlement should model downside scenarios
This issue begins with the contract and use of funds, not with the fact that the family owns the business. This issue begins with the contract and use of funds, not with the fact that the family owns the business. Default, enforcement and company insolvency should be considered before dividing liquid assets. The debt should be traced from creditor to borrower to actual use of funds before it enters the marital balance sheet. The most useful supporting records here are enforcement records, joint-account statements and company ledgers. [1][4]
A personal guarantee can expose the entrepreneur even where the underlying borrower is the company, while the other spouse may have no direct contractual liability. The Civil Code joint-debt framework and company personality should remain separate in the analysis. The agreement should therefore model what happens if the company defaults or a guarantee is enforced. The section should finish with the external enforcement risk and the internal allocation between spouses stated separately. Applied to “Settlement should model downside scenarios,” that produces a section-specific recommendation rather than a reusable evidence checklist. The settlement model should show how settlement should model downside scenarios affects creditor exposure before liquid family assets are distributed.
The joint-debt rules require proof of purpose when only one spouse borrowed
The Civil Code and the Supreme People’s Court interpretation on spousal debt distinguish obligations based on joint intent, ordinary household needs and borrowing beyond daily family needs. Where one spouse incurs debt in a personal name outside ordinary household consumption, the creditor may need to prove that the money was used for common life, common production and operation, or arose from the spouses’ common intention. [1][2]
That framework matters in a business-owner divorce because “used for the company” is not a complete answer. Counsel should identify whether the non-borrowing spouse participated in the business, whether household assets benefited, and how the money moved after receipt. A loan paid directly into a company account may have a different evidentiary profile from money transferred to a spouse and then used partly for family expenses.
The analysis also should not confuse the creditor’s external claim with the spouses’ internal allocation. Even where a debt is enforceable against one spouse, the divorce may address indemnity or reimbursement between them. Conversely, an agreement that one spouse will bear a debt does not eliminate a creditor’s rights. Keeping those two levels separate is essential to a realistic settlement.
Personal guarantees can change the economic fairness of an otherwise balanced property split
A company loan may sit entirely on the company’s balance sheet while a founder’s personal guarantee exposes the founder’s personal assets if the company defaults. In divorce, that contingent liability can affect the economic value of the assets allocated to the guarantor even if the non-borrowing spouse has no direct liability to the bank. Counsel should therefore identify outstanding principal, secured assets, guarantee scope, maturity and any existing enforcement or restructuring discussions. The Company Law and Civil Code joint-debt framework answer different parts of this problem. [1][2][3]
The divorce court does not need to predict with certainty whether the guarantee will be called, but the spouses should not divide liquid assets as though the risk does not exist. A reserve, staged equalization, security or indemnity may be justified where default is plausible. Conversely, a remote guarantee on a healthy company should not be used opportunistically to depress the other spouse’s share without evidence.
The settlement should also explain what happens if the risk later changes. If the bank releases the guarantee or the company repays the loan, a reserved amount may become payable. If enforcement occurs first, the indemnity or reserve should operate without requiring a new valuation of unrelated marital assets. This kind of contingency planning is not a statutory formula; it is a way to align the family settlement with a third-party credit exposure the spouses cannot control directly.
Case study: applying the framework
Assume the company owes RMB 8 million to banks and suppliers, the entrepreneur personally guaranteed RMB 3 million, RMB 700,000 of business payments passed through the couple’s joint account, and a friend transferred RMB 500,000 directly to the entrepreneur shortly before the company’s cash crisis.
The RMB 700,000 passing through the joint account should be reconstructed transaction by transaction because business use of a household account does not make the entire account or every business liability marital. The personal guarantee should be read from the bank contract, and the friend’s RMB 500,000 transfer should be traced to its purpose. If it went directly into company operations, the company’s accounting treatment may help explain the relationship; if it funded personal expenses, the analysis changes. Because creditors are not bound automatically by a divorce allocation, the spouses may need indemnities, security or a reserve of liquid assets to manage external enforcement risk after property division.
The couple should also examine whether any company receivables or pledged assets affect the entrepreneur’s ability to satisfy external creditors. That information can shape how much cash should remain available after divorce. If the spouse receives an indemnity for business liabilities, the agreement should identify the triggering event and security supporting reimbursement. A paper promise is weak protection if the entrepreneur’s company is already facing enforcement, so creditor risk should be modeled before the final asset split. The settlement would identify current creditor proceedings expressly so neither spouse relies on a cash balance already subject to enforcement.
Conclusion
Business debt should enter a divorce only after the debtor, guarantee, use of funds and creditor rights are identified. Company liabilities, personal guarantees and marital debt can overlap economically without being the same legal obligation. The spouses’ agreement can allocate risk internally, but it cannot eliminate a valid third-party claim. A realistic settlement therefore combines the joint-debt rules with company-law separation and models the consequences of enforcement before liquid family assets are distributed.
Legal and regulatory sources
[1] Civil Code of the People’s Republic of China — [official source](https://www.court.gov.cn/zixun/xiangqing/233181.html) [2] SPC Interpretation on Disputes Concerning Spousal Debts — [official source](https://www.court.gov.cn/fabu/xiangqing/77352.html) [3] Company Law of the People’s Republic of China (2023 revision) — [official source](https://www.npc.gov.cn/npc/c2/c30834/202312/t20231229_433999.html) [4] Civil Procedure Law of the People’s Republic of China — [official source](https://cicc.court.gov.cn/html/1/218/62/83/443.html)
General legal information only; not legal advice for a specific matter.
Discussion
Share experience or questions about this topic. This is a public discussion — not legal advice. Do not post confidential case details.
Have a question after reading? Leave it here, or Ask a Lawyer for a free initial intake.
Comments are moderated. China Legal Portal is a directory and information resource; no attorney–client relationship is formed by posting here.